 1-888-601-9980
- Manulife offers Manulife Par and Manulife Par with Vitality Plus, both providing permanent coverage
- Policyholders can choose 10-pay, 20-pay, pay-to-90, or pay-to-100, allowing them to select a premium schedule that fits their financial goals
- The minimum coverage is $100,000 for 10-pay, 20-pay, and pay-to-90 policies, while pay-to-100 policies require at least $500,000 in coverage
- The Manulife Par with Vitality Plus plan includes access to Manulife’s rewards program
- Both Manulife Par and Manulife Par with Vitality Plus offer riders for child protection, term insurance, guaranteed insurability, and total disability waiver
Manulife offers permanent life insurance through Manulife Par, a participating whole life insurance policy designed to provide lifetime protection while building cash value over time. The policy combines guaranteed premiums, a guaranteed death benefit, and cash value growth with the potential to earn annual dividends. Manulife whole life insurance plans also come with limited pay options such as pay 10, pay 20, pay-to-90, and pay-to-100. Eligible applicants can also choose Manulife Par with Vitality Plus, which adds Manulife’s wellness rewards program and additional Vitality-related benefits to the core Manulife Par coverage.
Quick review
- PolicyAdvisor ratings: 5/5
- Best for: Added wellness rewards through the Vitality program
- Skip if: You want a broader range of dividend options than cash or paid-up insurance
See how much whole life insurance coverage you can get
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by

About Manulife
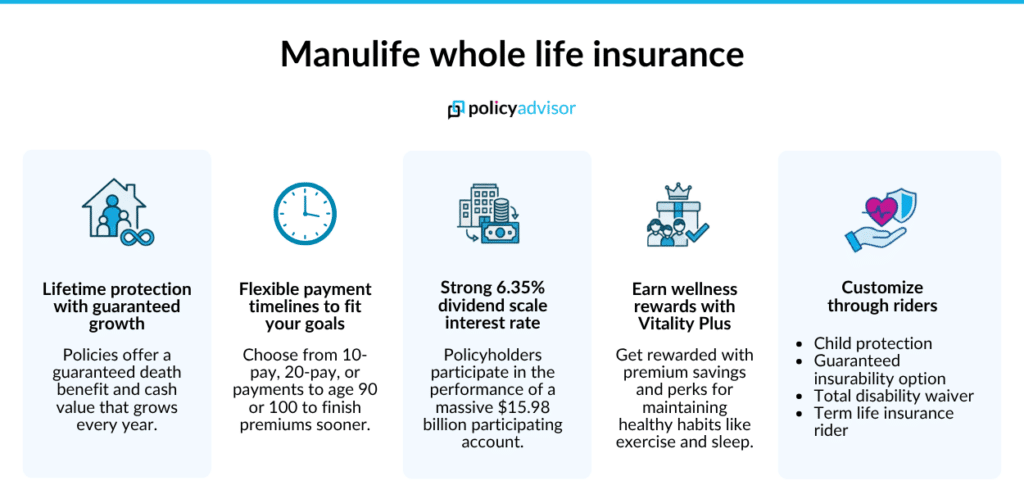
Manulife operates as one of Canada’s largest participating life insurance platforms, supported by a $15.98 billion participating account. Its participating whole life insurance policies allow policyholders to share in the performance of the participating account through annual policy dividends, subject to the insurer’s dividend scale. For 2026, Manulife has maintained a 6.35% DSIR for participating whole life insurance policies.
Manulife’s financial strength
| AM Best Rating | A+ |
| Participating account fund size | $15.98 billion |
| LICAT ratio | 136% |
| Dividend scale interest rate (DSIR) | 6.35% |
Disclaimer: Figures and ratings are based on the latest available information and may change over time
What is Manulife whole life insurance?
Manulife whole life insurance is permanent life insurance that stays in place for life as long as the policy remains in force. Manulife’s core plan name is Manulife Par, and there is an option to opt for Manulife Par with Vitality Plus, which provides access to Manulife’s Vitality program. Both options offer cash value growth and guaranteed access to cash value in the early years. For 10-pay, 20-pay, and pay to age 90 plans, the coverage starts at $100,000. For pay to age 100, the coverage starts at $500,000.
Manulife Par with Vitality Plus™ gives the policyholder individual access to the maximum-value benefits of Manulife Vitality, the company’s flagship rewards program. Manulife Par with Vitality Plus™ offers only single life coverage, while Manulife Par offers single life and joint-last-to-die coverage options.
Key features of Manulife whole life insurance
| Policy issue age (min & max) |
|
| Coverage range (min) |
|
| Coverage options |
|
| Payment options |
|
| Policy fee | None |
| Dividend options | Cash or paid-up insurance (PUI) |
| Deposit option | Available with the paid-up insurance dividend option, subject to limits and administrative rules |
| Premium offset | Available. Uses the policy’s built-up value to help pay future premiums |
| Monthly Vitality charges |
– $15 for pay 10 years – $10 for pay 20 years – $6 for pay to age 90 – $4 for pay to age 100 |
| Riders |
|
Who is eligible for Manulife whole life insurance?
Manulife whole life insurance is available to those who meet the following requirements:
- Canadians who meet Manulife’s underwriting requirements
- Individuals aged between 0 and 80 years and 18-80 years for Manulife Par with Vitality Plus
- Individuals seeking at least $100,000 in coverage, although minimum coverage varies by payment option
What is covered under Manulife whole life insurance?
Manulife whole life insurance provides lifelong financial protection, with the policy’s key benefits including:
- Lifetime coverage: A guaranteed death benefit is paid to beneficiaries when the insured dies, or after the last death for joint last-to-die coverage
- Guaranteed cash value: The policy builds guaranteed cash value over time that can be accessed through withdrawals or policy loans
- Potential dividends: Participating policies may receive non-guaranteed dividends that can be taken as cash or used to purchase additional paid-up insurance
- Optional riders: Additional protection can be added through riders such as term insurance, total disability waiver, guaranteed insurability, and child protection riders
- Vitality benefits: Eligible policyholders can access wellness features and rewards through Manulife Vitality, depending on the policy and the insured person’s Vitality Status
Types of Manulife Par whole life insurance
Manulife’s core participating whole life insurance product is Manulife Par, with an enhanced version that has Vitality Plus built in.
- Manulife Par: A participating whole life insurance plan that provides lifetime coverage, guaranteed premiums, guaranteed cash value growth, and a guaranteed death benefit. Policyholders may also receive annual dividends, which can be used to enhance the policy’s cash value and insurance coverage. The available coverage options are single life or joint last-to-die and include Vitality Go™ at no additional cost. The Vitality Go™ rewards you for leading a healthy lifestyle. Also, note that Vitality Go members can upgrade to Manulife Par with Vitality Plus anytime before the policy’s third anniversary
- Manulife Par with Vitality Plus: This version keeps the core participating whole life features of Manulife Par while building the Vitality Plus wellness program into the policy. With this policy, policyholders can earn rewards for participating in activities that promote healthier living, while the policy continues to provide guaranteed benefits and the potential for annual dividends. Manulife Par with Vitality Plus is available as single life coverage only
Manulife Par and Manulife Par with Vitality Plus:
| Features | Manulife Par | Manulife Par with Vitality Plus |
| Coverage amount | Starts at $100,000 for 10-year, 20-year, and pay-to-age-90 durations; $500,000 for pay-to-age-100 | Starts at $100,000 for 10-year, 20-year, and pay-to-age-90 durations; $500,000 for pay-to-age-100 |
| Payment duration options | 10 years, 20 years, to age 90, or to age 100 | 10 years, 20 years, to age 90, or to age 100 |
| Coverage options | Single life or joint last-to-die | Single life only |
| Eligibility for Vitality benefits | Access to Manulife Vitality Go™ benefits at no added cost | Access to maximum-value Manulife Vitality benefits |
| Upgrade option | Upgrade to Manulife Par with Vitality Plus before the 3rd anniversary (no underwriting required) | Not applicable |
| Issue age | 18-80 years | 18-80 years |
| Monthly Vitality® charge | Not applicable | – $15 for pay 10 years
– $10 for pay 20 years – $6 for pay to age 90 – $4 for pay to age 100 |
| Dividend options | Paid-up insurance or cash | Paid-up insurance or cash |
Pros and cons of Manulife whole life insurance
Manulife’s participating whole life policies offer a range of benefits such as immediate cash value growth, the option to choose the frequency and duration of premiums, and access to riders. Manulife also offers deposit option payments where the insured individuals can make direct premium payments and increase their protection.
A downside of Manulife’s whole life insurance is that Manulife does not offer non-participating plans, and some policy owners may find the dividend and returns structure complex.
| Pros | Cons |
| Choose from 10-pay, 20-pay, pay-to-90, and pay-to-100 options to match different financial goals | They offer only two dividend options, while other insurers typically offer more |
| Deposit option payments are available where policy owners can make additional premium payments to increase protection | Pay to age 100 requires at least $500,000 in coverage |
| Variety of riders offered by Manulife for different life events and needs | Joint coverage is not available with Vitality Plus |
| Manulife Par with Vitality Plus can provide wellness rewards and benefits in addition to life insurance coverage | |
| Available as single-life or joint-last-to-die coverage, depending on the policy type | |
| Immediate cash value growth and guaranteed cash value in the early years |
How much does Manulife whole life insurance cost?
The cost of Manulife whole life insurance for a 20-pay whole life insurance policy with $100,000 in coverage ranges from $246.20 to $620.71 per month. In the table below, we have listed the cost for a male and a female and how they vary with age.
Cost of Manulife whole life insurance (2026):
| Age (in years) | Male | Female |
| 20 | 246.20/month | 226.04/month |
| 30 | 291.59/month | 266.35/month |
| 40 | 331.71/month | 319.26/month |
| 50 | 394.61/month | 380.76/month |
| 60 | 459.84/month | 441.20/month |
| 70 | 678.46/month | 620.71/month |
*Illustrative monthly premiums for $100k of participating whole life insurance with a 20-pay premium period
What riders are available with Manulife whole life insurance?
Manulife offers several optional benefits with its whole life insurance, including waiver of premium, guaranteed insurability, child coverage, and additional term insurance.
- Total disability waiver rider: This rider can waive Manulife Par premiums if the insured becomes totally disabled for six months or longer. If the disability begins before age 60, premiums can be waived for as long as the disability continues. If total disability begins after age 60, premiums are waived until age 65, subject to the rider’s terms and conditions
- Guaranteed insurability option rider: This option allows you to purchase additional life insurance in the future without providing new medical evidence of insurability. The option can generally be exercised up to eight times on specified option dates in the policy contract or following qualifying life events, such as marriage or the birth or adoption of a child
- Child protection rider: This rider provides $10,000 of life insurance coverage for an eligible child of an insured person covered by the policy. When the child reaches age 25, they can purchase up to $250,000 of new life insurance coverage without additional underwriting, including up to $100,000 of critical illness coverage
- Term insurance rider: This option adds temporary term life insurance coverage to the permanent whole life policy. The coverage is available on a 10-year or 20-year renewable basis and can be structured on a single-life or combined basis. Through this, policyholders can convert the term coverage to a permanent Manulife life insurance plan available at the time of conversion up to age 75 without providing evidence of insurability
What factors affect the performance of Manulife’s participating account?
Manulife’s participating account is influenced by four key factors that can affect its performance and, ultimately, policy dividends:
- Claims experience: Higher-than-expected death claims can reduce the account’s funds, while lower claims can have a positive effect
- Policy cancellations: The number of policies cancelled or surrendered can affect the account’s expected cash flow and performance
- Expenses and taxes: Underwriting, administration, policy servicing, operating costs, and taxes affect the account’s overall performance
- Investment returns: Investment performance is a major factor. Returns above expectations can strengthen the account, while lower-than-expected returns can negatively affect it
Factors that influence Manulife’s participating accounts
| Factor | Predictability | Stability | Impact on performance |
| Claims experience | High | High | Low |
| Cancellations | Medium | Medium | Medium |
| Expenses & Taxes | High | High | Low |
| Investment Returns | Medium | Medium | High |
Does Manulife Par offer a disability benefit?
Yes, Manulife Par includes a built-in Disability Benefit that allows policyholders to access a portion of their policy’s cash value. The benefit can provide financial support if the insured becomes disabled.
To qualify, the insured must generally meet the definition of total disability or catastrophic disability:
- Total disability (ages 18 to 65): The insured is unable to perform their regular occupation or, if unemployed, their regular daily activities
- Catastrophic disability (from age 18): The insured is unable to perform an activity of daily living or experiences the total and permanent loss of sight, hearing, speech, or use of their hands or feet, or suffers qualifying cognitive impairment
This benefit comes with a 30-day elimination period, and only one payment can be made in any 12-month period. Since payments are taken from the policy’s cash value, each payment will also reduce the policy’s death benefit.
What is Manulife Vitality?
Manulife Vitality is a wellness-enhanced insurance program that rewards policyholders for maintaining healthy habits. It’s designed to encourage better lifestyle choices and make wellness a part of your insurance experience.
When you are enrolled, you earn Vitality Points for completing everyday health activities like walking, exercising, getting a flu shot, sleeping well, or meditating. As your points increase, your Vitality Status improves from Bronze to Silver, Gold, and Platinum, unlocking greater rewards and premium savings. These can include discounts on leading brands, fitness devices, and even travel or entertainment perks.
There are two versions of the program: Vitality Go™, which is included at no cost with all eligible plans, and Vitality Plus™, which offers enhanced benefits and exclusive rewards, such as the opportunity to earn a free Apple Watch®, for a small monthly fee. Manulife Vitality is also available with health and dental insurance to help members integrate wellness into both their financial and physical health goals.
What premium options does Manulife offer?
Manulife Par offers four payment schedules: 10-pay, 20-pay, pay to age 90, and pay to age 100. Each one lets you finish paying for the policy on a different timeline.
- 10-pay: Premiums are payable for 10 years, after which the policy becomes paid-up for life
- 20-pay: Premiums are payable for 20 years, and the policy is fully paid-up once that period ends
- Pay to age 90: Level premiums continue until the insured reaches age 90, with lifetime coverage following the final payment
- Pay to age 100: Level premiums continue until age 100. This option typically includes a higher minimum coverage amount, often $500,000 or more
For 10-pay, 20-pay, and pay to age 90, the coverage starts at $100,000, while for pay to age 100, the minimum coverage is $500,000.
Can a Manulife Par joint last-to-die policy be replaced with a single-life policy?
Yes, a Manulife Par joint last-to-die policy can be replaced with one or two single-life Manulife Par policies. This can be done without new evidence of insurability if their marriage or business partnership ends. This can help each policyholder maintain individual permanent life insurance coverage after the relationship or partnership is dissolved. The replacement option is available before the fifth policy anniversary, provided the policyholders are 65 or younger, and the original joint policy has a standard joint rating. Manulife must approve the replacement.
Can you change the premium payment period on a Manulife Par policy?
Yes, Manulife Par policyholders may be able to change their premium payment period to a longer duration, subject to Manulife’s administrative rules and policy conditions. The available changes include:
- 10-pay → 20-pay: Change from paying premiums for 10 years to paying them for 20 years. Request must be received before the 5th policy anniversary
- 10-pay → Pay-to-90: Extend the premium payment period from 10 years to payments up to age 90. Request must be received before the 5th policy anniversary
- 20-pay → Pay-to-90: Change from a 20-year premium period to payments up to age 90. Request must be received before the 10th policy anniversary
This option can help policyholders spread their premium payments over a longer period, potentially making the ongoing premium commitment more manageable. Moreover, you cannot change to a shorter premium duration, switch to Pay to age 100, or change only part of the policy’s premium duration. Changing the premium duration will also reduce the policy’s guaranteed cash value, with the released amount refunded to the policy owner.
Does Manulife Par offer compassionate assistance?
Yes, Manulife Par includes a complimentary, non-contractual Compassionate Assistance Program. If the insured person becomes terminally ill and death is imminent, the policy owner may request early access to a portion of the death benefit through a collateral loan from Manulife.
The loan is provided on a tax-free basis, subject to applicable tax laws, with the policyholder responsible for the loan interest and any physician fees required to complete the application. The policy remains in force after the loan is provided, but the outstanding loan amount plus accrued interest is deducted from the death benefit payable to beneficiaries. Once a Compassionate Assistance loan has been issued, no further withdrawals can be made from the policy under this benefit.
Compare dividend rates from top Canadian insurers
| 2022 | 2023 | 2024 | 2025 | 2026 | |
|---|---|---|---|---|---|
| Equitable | 6.05% | 6.25% | 6.40% | 6.40% | 6.40% |
| Manulife | 6.10% | 6.35% | 6.35% | 6.35% | 6.35% |
| iA Financial Group | 5.75% | 6.00% | 6.25% | 6.35% | 6.35% |
| Desjardins Insurance | 5.75% | 6.20% | 6.30% | 6.30% | 6.30% |
| RBC Insurance | 6.00% | 6.00% | 6.25% | 6.30% | 6.30% |
| Sun Life | 6.00% | 6.00% | 6.25% | 6.25% | 6.25% |
| Empire Life | 6.00% | 6.00% | 6.00% | 6.25% | 6.25% |
| Foresters Financial | 5.50% | 5.50% | 5.50% | 6.25% | 6.25% |
| Co-operators | 5.90% | 5.90% | 6.00% | 6.00% | 6.00% |
| Assumption Life | 5.75% | 5.75% | 5.75% | 5.75% | 5.80% |
| Canada Life | 5.25% | 5.50% | 5.50% | 5.75% | 6.00% |
Powered by
How does Manulife compare to other whole life insurance providers?
Manulife whole life insurance stands out for its participating Manulife Par product, multiple premium payment options, and guaranteed cash value growth. Its 10-pay, 20-pay, pay-to-90, and pay-to-100 options give you flexibility to match premium payments with your long-term financial goals. It also offers Manulife Par, with Vitality Plus adding wellness features and rewards to your whole life insurance plan. To see how Manulife compares with other leading insurers, read our guide to the best whole life insurance companies in Canada.
Our advisor’s take on Manulife whole life insurance
At PolicyAdvisor, one of our advisors recently helped a client, aged 45, who was looking for permanent life insurance with a clear premium payment timeline. The client’s primary goal was to finish paying for the policy before retirement while keeping lifelong coverage in place.
Client profile:
- Age: 45-year-old non-smoking Canadian
- Coverage need: $500,000 in permanent coverage to support family protection and long-term estate planning
- Primary concern: Finishing premium payments before retirement while keeping lifelong coverage in place
- Our comparison: We compared Manulife Par with participating whole life products from other leading Canadian insurers, focusing on premium payment periods, guaranteed values, dividend potential, and available riders and benefits
Why Manulife stood out:
- Multiple premium payment periods, including 10-pay, 20-pay, pay-to-90, and pay-to-100, allowing the client to choose a premium schedule that fits their long-term financial goals. For this client, the shorter payment options made it possible to structure the policy so premiums could be completed before retirement while the coverage stayed in force for life.
- Lifetime coverage with guaranteed values, providing permanent protection along with guaranteed cash value growth
- Manulife Vitality Plus option, providing wellness features and rewards that encourage healthy living while adding value to the permanent life insurance policy
- Flexible policy enhancements, including the Guaranteed Insurability Option, Term Insurance Rider, Total Disability Waiver, and Child Protection Rider, allowing the client to adapt coverage to changing needs
How to buy Manulife whole life insurance?
To apply for a Manulife whole life plan, you would need to choose the plan type (Manulife Par or Manulife Par with Vitality Plus™), choose your coverage options, fill in an application form, and submit it. Your policy may also require medical underwriting based on your plan specifics.
For the best Manulife whole life insurance policy quotes, speak to our experts at PolicyAdvisor. Our licensed advisors will help you choose a plan and coverage options that best suit your needs and budget. We will also support you with the application, making the entire process seamless and easy for you!
Frequently asked questions
Does Manulife offer participating policies with dividends?
Yes, Manulife offers participating whole life policies with dividends. Dividends can either be used to buy more insurance, or they can be withdrawn as cash. In case policy owners choose to withdraw the dividends, there may be some tax implications.
Is Manulife whole life worth it?
Yes, Manulife’s whole life insurance can be worth it, especially for people looking for a policy that builds cash value and provides long-term protection at affordable rates. Their policies are designed to help build wealth with dividend options that can be used to either buy more insurance or be withdrawn as cash. Manulife also offers exclusive benefits with its Vitality program, making its whole life insurance plans an ideal option for those looking for complete protection.
Can you borrow against the cash value?
Yes, you can request a cash loan, which is typically subject to Manulife’s administrative rules. The maximum amount you may borrow is 90% of the total available cash value minus any outstanding policy loan balance.
What are the premium payment options for Manulife whole life insurance?
Manulife Par offers four premium payment options: 10-pay, 20-pay, pay-to-90, and pay-to-100. This allows policyholders to select a payment schedule based on their financial goals and how quickly they want to complete premium payments.
What riders are available with Manulife whole life plan?
Manulife Par offers optional benefits such as the term insurance rider, total disability waiver, guaranteed insurability option, and child protection rider. These options can provide additional protection or help policyholders increase their coverage as their needs change, but they come with additional premiums.
What is Manulife Par with Vitality Plus?
Manulife Par with Vitality Plus combines participating whole life insurance with a wellness program that rewards eligible policyholders for healthy-living activities. It provides the same core whole life insurance features of Manulife Par while adding wellness-related benefits and rewards. It is available on a single life basis only.
What dividend options does Manulife offer?
Manulife offers paid-up insurance and cash that can be taken out or used for premium reduction. If you choose the paid-up insurance option, your annual dividends are used to automatically buy additional, fully paid-up insurance. This means that once your dividends have been used to purchase additional coverage, you do not need to make any further premium payments for the paid-up insurance. If you choose the cash option as your dividend strategy, the annual dividends you receive are paid directly to you. In this case, there may be some tax implications.
How are Manulife’s whole life insurance dividends distributed?
Dividends are allocated to Manulife Par policyholders using a dividend scale. A dividend scale is a formula used by all insurance companies to fairly and equitably distribute the dividends among all the policy owners. The dividend scale is not guaranteed and usually increases or decreases based on the participating account’s performance.
Where does Manulife invest the participating account’s premiums?
Manulife invests the participating account’s funds in public bonds, real estate, public and private equities, mortgages, and private debt. This diversified portfolio helps generate steady long-term returns while maintaining stability for policyholders.
Manulife offers two whole life insurance options: Manulife Par and Manulife Par with Vitality Plus™. Both provide permanent lifetime coverage, guaranteed cash value growth, and flexible premium payment options, including 10-pay, 20-pay, pay-to-90, and pay-to-100. Manulife Par policies can also earn non-guaranteed dividends, while Manulife Par with Vitality Plus adds wellness features and rewards.