 1-888-601-9980

Compare & Buy Canada’s Best Term Life Insurance





Trusted by Canadians
What is life insurance?
Life insurance is a contract between you and an insurer. In exchange for premiums, the insurer provides a death benefit to your designated beneficiary if you die while the policy is in force, subject to the contract’s terms and conditions. A death benefit paid to an individual beneficiary is generally received tax-free in Canada, but tax treatment can depend on the ownership and circumstances of the policy.
Life insurance can be especially important when family members or others depend on your income. Your beneficiary can use the benefit to help replace lost income, cover household expenses, pay outstanding debts or support long-term financial goals.
Recognized as a leader in the industry



Types of life insurance in Canada
Life insurance generally falls into two broad categories: term life insurance and whole life insurance. Besides these two main life insurance options, there are other types of life insurance policies with very specific use-cases, such as universal and Term-to-100 insurance.
Term life insurance
Term life insurance covers you for a fixed period of time such as 10, 20, or 30 years, or until you reach a set age, like 65 years old. You pay premiums periodically during that term and should you pass away, your beneficiaries will receive a tax-free lump sum payment according to the policy terms. Term coverage is commonly used for temporary financial responsibilities, such as mortgage payments or raising children.
Learn more about term life insurance
Whole life insurance
Whole life insurance covers you for your entire life, rather than a set term. It provides permanent coverage and typically includes a cash value component. You pay premiums periodically until your death or until you surrender the policy for its accumulated cash value. It may suit people seeking lifelong coverage and certain estate-planning or legacy objectives.
Learn more about whole life insurance
Universal life insurance
Universal life insurance is similar to whole life insurance, except there is a self-directed long-term investment component. It combines permanent life coverage with an investment component. Your insurer gives you options for investing the cash value of your policy. Universal life insurance plans require more hands-on activity than other life insurance coverage options.
Learn more about universal life insurance
Term-to-100 life insurance
Term-to-100 insurance is a form of permanent coverage designed to provide protection to age 100. Unlike many whole life policies, it does not build cash value and only pays upon your death. It basically offers a bridge between term and whole life insurance. Plus, if you make it to 100 years, you are no longer required to pay premiums and still retain the coverage.
Learn more about term-to-100 life insurance

What is better: Term or Whole life insurance?
There is no single best option for everyone. Term life insurance may be suitable when you need substantial coverage for a limited period. Whole life insurance may suit people who want permanent protection and have a need for the additional features of a permanent policy. One must compare the coverage, premiums, policy guarantees and flexibility before choosing.
Need insurance answers now?
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them.
Do I need life insurance in Canada?
Life insurance can help protect the people who depend on your income or financial support. The main reasons Canadians purchase a life insurance policy are:
- Help pay off their debts
- Provide for their children’s education
- Every day expense of your partner who relies on your earnings
- Pay for their funeral arrangements
- Protect their business
Even if no one depends on your income today, you may have other goals, such as covering final expenses or leaving money to a beneficiary. Whether you need coverage, and how much, depends on your circumstances, budget and existing financial resources.
How much life insurance do I need in Canada?
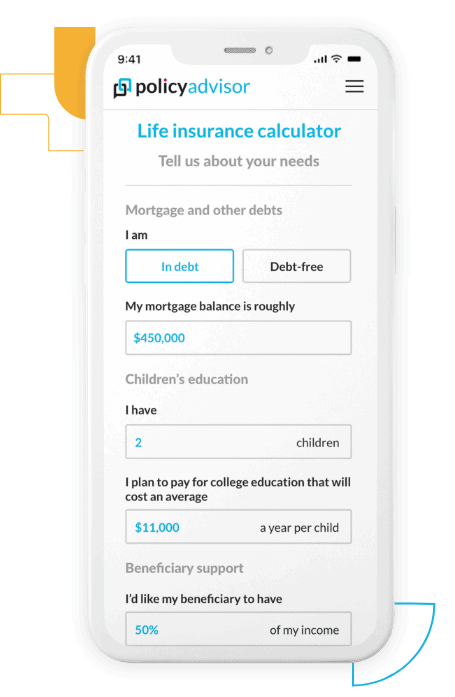
The right amount of life insurance depends on your financial responsibilities, your dependents’ needs and the resources already available to them. You don’t want to choose so little as to not cover any outstanding debts as well as the cost of living for those you leave behind. At the same time, choosing an amount that’s too large may prove costly for the premiums you pay while you are alive.
Consider how long your family would need financial support and whether your current coverage would be enough. A common rule of thumb is to choose 8-10 times your yearly income as your death benefit. Below are the things to consider when figuring out life insurance needs:
Below are the things to consider when figuring out life insurance needs:
- Outstanding debts, including mortgages and other loans
- Income your family may need to replace
- Future expenses, such as childcare and education
- Final expenses and other financial obligations
- Existing life insurance, savings and other resources
Is life insurance through work enough?
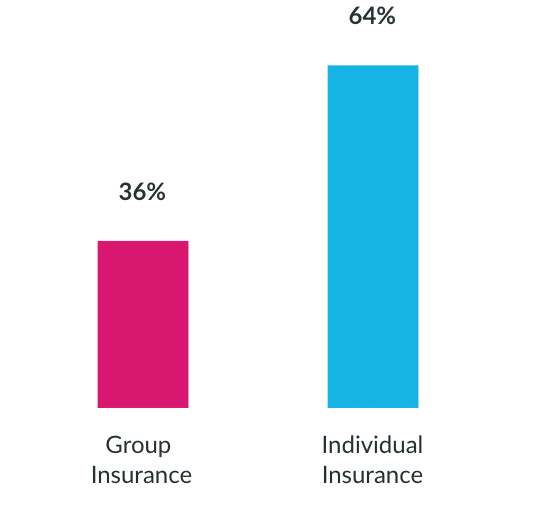
While group plans are affordable, convenient, and require limited to no underwriting, they offer limited coverage, a lack of control, and severely limited portability. If you leave your job or retire, you most likely lose your coverage or face a pricey conversion option.
Most workplace benefit plans offer 1-2 years of their salary as a death benefit. Most Canadians with dependents would need substantially more coverage to adequately provide for those they leave behind should something unfortunate happen to them.
Hence, the majority of Canadians may find themselves with a gap in coverage if they examine their group plans versus their needs.
How much does life insurance cost?
For most young, healthy adults life insurance costs are quite reasonable on a 20-year term policy. However, most people overestimate the cost of life insurance (by up to five times the actual price!). The reality is, rates can be as low as the cost of an extra-large pizza every month.
For instance, a 30-year old, non-smoking Ontario woman of average health, would only pay $21 per month for a $500,000 coverage on a 20-year policy. The price for 20-year term life insurance will be only14$ if she chooses a $250,000 coverage amount. Learn more about life insurance costs in Canada.
| COVERAGE AMOUNT |
TERM 10 YEARS |
TERM 20 YEARS |
| $250k | $11/mo | $14/mo |
| $500k | $15/mo | $21/mo |
| $1M | $23/mo | $36/mo |
To get an accurate picture of how much your life insurance options might cost for you, use our life insurance quote tool. By answering a few questions you can get no-obligation quotes from 30 of Canada’s top insurance companies.
How to compare life insurance quotes in Canada
When comparing life insurance quotes, look at more than the monthly premium. Compare the coverage amount, policy duration, guaranteed premiums, exclusions, renewal and conversion options, and any features you may need in the future. Make sure the quotes are based on comparable coverage so you can judge the options fairly.
What affects the cost of life insurance in Canada?
Several factors determine the cost of life insurance, but they can be divided into 2 buckets: personal (your health status and other factors unique to you) and policy (the type and amounts of coverage you choose).
What is the best life insurance Canada has to offer?
There is no best life insurance provider as there is no single best policy for everyone. There is – however – the best life insurance provider for you. depends on your coverage needs, budget, health and preferred policy features.
PolicyAdvisor helps you find the best life insurance policy for your needs. We have partnered with 30+ of Canada’s top insurance companies to make sure you have the greatest number of options when choosing the insurance company to protect yourself and your loved ones.
To help you compare your options, we have also rated the leading Canadian life insurance providers and evaluated their products, features and suitability for different needs. Read our detailed guide to the best life insurance companies in Canada (2026) to explore our top picks, compare insurers and understand which companies may be right for you.

Which companies provide life insurance quotes on PolicyAdvisor?
We show you quotes from the best life insurance companies in Canada. This includes some of the most trusted insurance providers, such as:




Why choose PolicyAdvisor for a life insurance quote in Canada
Getting a life insurance quote shouldn't feel complicated. Here's why Canadians choose PolicyAdvisor:
No waiting for callbacks. No hidden pricing. Compare personalized insurance quotes upfront.
View multiple options side-by-side and find the best, most affordable option for your financial safety.
Your premiums stay fair and clear.
Explore your options without any pressure to buy.
Start your quote online in minutes and complete your application seamlessly.
Have questions? Speak to a licensed advisor for guidance anytime you need it.
How to get life insurance through PolicyAdvisor
Tell us what coverage you need:
Provide the basic information required to explore available life insurance options.
Compare available quotes:
Review personalized options and compare premiums, coverage and policy features.
Get help from an advisor:
Discuss your options, ask questions and decide how you would like to proceed.
Is life insurance worth it?
Life insurance is totally worth it if someone depends on your income for financial support. It can provide a financial safety net for your family if you pass away, helping them manage everyday expenses, pay outstanding debts, cover childcare or education costs, and maintain their standard of living.
For example, parents with young children, homeowners with a mortgage, and individuals whose partners rely on their income may benefit from having coverage. People with fewer financial obligations or sufficient savings to support their dependents may need less coverage.
The type of policy you choose also matters. Term life insurance can provide affordable protection during specific financial milestones, such as raising children or paying off a mortgage. Permanent life insurance, such as whole life insurance, may suit people who need lifelong coverage and have longer-term financial or estate-planning goals.
Frequently asked questions

Go to our online life insurance comparison tool and answer a few basic questions and you’ll be able to compare the best life insurance quotes and a life insurance policy from more than 30 of Canada’s largest life insurance providers. You can get a quote in minutes.