 1-888-601-9980
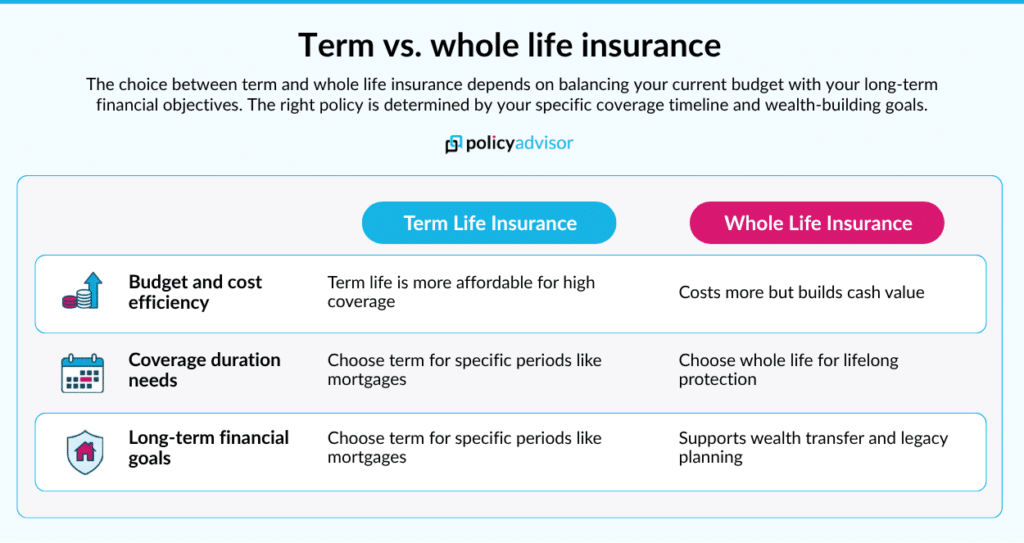
- Term life insurance is generally more affordable and suits temporary needs such as mortgages, debts, and income replacement
- Whole life insurance provides lifelong coverage, cash value growth, and a guaranteed death benefit when the policy remains in force
- You can combine term and whole life insurance to cover both temporary and permanent financial needs
- Many term policies can be converted to permanent coverage without new medical underwriting, subject to the policy’s terms
Term life insurance provides coverage for a set period, while whole life insurance provides lifelong coverage. Term insurance generally has lower premiums and no cash value and is a good choice for those looking for affordable coverage. Whole life insurance costs more but can build cash value and provides a guaranteed death benefit when the policy remains in force.
Term vs whole life insurance:
Length of coverage:
- Term life: Covers for a fixed period
- Whole life: Covers for the entire life
Costs:
- Term life: More affordable option
- Whole life: More expensive than term life
Cash value:
- Term life: No cash value
- Whole life: Builds cash value over time
What is term life insurance?
Term life insurance covers a specific period, such as 10, 20, or 30 years. If the policyholder passes away during this term, a death benefit is paid to beneficiaries, but there is no payout if the term ends while the policyholder is still alive. This makes term insurance ideal for temporary needs like paying off a mortgage or funding education.
How much does term life insurance cost?
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by

Benefits of term life insurance
- Term insurance generally costs less than whole life insurance for the same coverage amount
- Term insurance primarily provides a death benefit for a defined period, making it relatively straightforward to understand
- Many term policies allow you to convert coverage to permanent insurance without new medical underwriting, subject to the policy’s terms
How does term life insurance work?
Suppose a 35-year-old man purchases a $500,000 20-year term life insurance policy. If he dies while the policy is in force, his beneficiaries would generally receive the $500,000 death benefit. If he lives beyond the 20-year term, he would typically no longer have coverage unless he renews, converts, or replaces the policy.
Pros and cons of term life insurance
| Pros | Cons |
| Affordable premiums compared with permanent life insurance | No cash value or investment component |
| Simple and easy to understand with straightforward coverage | Renewal premiums can increase significantly after the initial term |
| Flexible term lengths such as 10, 20, or 30 years | No payout if you outlive the policy term |
| Can often be converted to permanent insurance without new medical underwriting, subject to the policy terms | |
| Suitable for temporary financial needs such as mortgages, debts, or income replacement |
What is whole life insurance?
Whole life insurance, by contrast, offers lifelong coverage and includes a cash value that grows over time, which can be accessed during the policyholder’s life. Its higher premiums reflect the added savings element and guaranteed protection, making it suitable for long-term goals like estate planning and legacy building.
What is your Whole Life Insurance worth?
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by
Benefits of whole life insurance
- Whole life insurance is designed to provide coverage for the insured’s entire lifetime, provided the policy remains in force
- The policy provides a guaranteed death benefit when its conditions are met, giving beneficiaries a predictable amount
- Whole life policies build cash value over time, which may be accessible during the policyholder’s lifetime, subject to the policy terms
- Participating whole life policies may receive dividends, which can provide additional options for using policy values
How does whole life insurance work?
Suppose a 40-year-old man purchases a $500,000 whole life insurance policy. As long as he pays the required premiums and the policy remains in force, his beneficiaries would generally receive the $500,000 death benefit when he dies. Unlike term life insurance, the policy does not expire after a set number of years. It continues to provide coverage for his lifetime, while its cash value builds over time and may be accessible during his lifetime, depending on the policy terms.
Pros and cons of whole life insurance
| Pros | Cons |
| Provides lifelong coverage as long as the policy remains in force | Higher premiums than term life insurance |
| Builds cash value over time that may be accessed during the policyholder’s lifetime | Less flexible than universal life insurance for changing premiums and coverage |
| Can support estate planning and legacy goals | May not be suitable for people who only need temporary coverage |
| Limited-pay options can allow policyholders to finish paying premiums within a set period while keeping lifetime coverage | |
| Offers guaranteed death benefits and, depending on the policy, guaranteed cash values |
Term vs whole life insurance: Key differences
Whole life and term life insurance differ in premium payment, dividends, coverage period, cash value, and a few other features. The table below outlines these differences.
Term vs whole life insurance
| Features | Term life | Whole life |
| Coverage period | Temporary coverage for a fixed time period, e.g. 10 years, 20 years, 25 years | Guaranteed lifelong coverage |
| Suitable for | Best suited for temporary needs (mortgage, children’s education, lifestyle protection) | Best suited for permanent needs (estate planning, retirement income, final expenses) |
| Premium payments | Low premiums for the initial term | Higher premiums because of lifetime coverage and savings component |
| Premium structure | Usually level during the selected term | Usually fixed for the life of the policy |
| Death benefit & cash value | Death benefit but no cash value component | Death benefit and access to a growing cash value |
| Dividends | No | May be available with participating policies |
| Conversion | Many policies offer conversion to permanent insurance | Already a permanent policy |
| Policy loans | No | May be available |
| Death benefit payout | Death benefit payout not guaranteed; you can outlive your policy | Guaranteed death benefit payout |
| Renewal | Usually available, depending on policy | Usually not required, as coverage is already permanent |
How much do term and whole life insurance cost?
The cost of life insurance ranges from $10.08 to $86.85 per month for term life insurance and $70.74 to $317.15 per month for whole life insurance, for $100,000 in coverage for a 20-year term and 20-pay respectively. For the same coverage amount, term life insurance generally costs less than whole life insurance. As age increases, premiums for both types rise, but whole life consistently remains more expensive due to its lifelong coverage and cash value component.
Term vs whole life insurance (2026)
| Age (in years) | Term life | Whole life |
| 20 | $10.08/month | $70.74/month |
| 30 | $10.35/month | $100.35/month |
| 40 | $14.13/month | $141.66/month |
| 50 | $29.43/month | $223.61/month |
| 60 | $86.85/month | $317.15/month |
Disclaimer: Premiums shown are illustrative monthly rates for a healthy, non-smoking male purchasing $100,000 in coverage for a 20-year term and 20-pay for whole life. Actual premiums vary based on factors such as age, gender, medical history, lifestyle, insurer, and more.
Why is term life insurance less expensive than whole life insurance?
Term life insurance generally costs less than whole life insurance because:
- Limited coverage period: Term insurance covers you for a specific period, such as 10, 20, or 30 years, rather than for life
- No cash value: Term policies generally do not build cash value like a whole life insurance policy
- Simpler policy structure: Term insurance primarily provides a death benefit without the additional features of permanent life insurance and is hence easy to manage
- Lower long-term risk to the insurer: The insurer only provides coverage for the selected term, rather than for the insured’s entire lifetime
- Whole life provides more features: Whole life insurance includes lifelong coverage, a guaranteed death benefit, and cash value growth, which contribute to its higher premiums
How to choose between term life and whole life insurance?
The decision regarding which one to choose between term life and whole life insurance is dependent on you. To determine which policy is right for you, consider your budget, coverage needs, and long-term financial goals.
- Your budget: Term life insurance is generally more affordable and may be suitable if you need substantial coverage at a lower cost. Whole life insurance costs more but provides lifelong coverage and builds cash value
- Your coverage needs: Choose term life if you need protection for a specific period, such as while paying a mortgage or supporting dependent children. Whole life may be better if you need coverage for your entire lifetime
- Your long-term financial goals: Term insurance may suit those focused on affordable financial protection, while whole life can support goals such as cash value growth, wealth transfer, and legacy planning
Can you have both term and whole life insurance?
Yes, you can have both term and whole life insurance policies. You can use a laddering strategy where you combine policies with different coverage amounts and term lengths to match your changing financial needs. For example, you could have a $750,000 20-year term policy for income protection and mortgage payments, along with a $100,000 whole life policy for lifelong needs such as final expenses or estate planning. As temporary financial obligations decrease, the term coverage can expire while the whole life policy continues to provide permanent coverage.
Can you convert from term to whole life insurance?
Yes, you can convert from a term life policy to a whole life insurance policy. Most of the insurers let you convert your term policy to a permanent policy like whole life insurance, without any additional medical evidence. However, conversion options vary by insurer and policy.
Age limits, conversion deadlines (typically up to 71 years of age), eligible permanent products, and the amount of coverage you can convert may apply, so check your policy’s terms before making a decision. Because whole life insurance generally has higher premiums than term insurance, your premiums are most likely to increase after conversion.
Our advisor’s take on term vs whole life insurance
Recently, one of our PolicyAdvisor advisors worked with a 40-year-old Canadian who wanted life insurance to protect their family while keeping premiums affordable. The client first wanted to understand the difference between temporary and lifelong coverage and then choose a policy.
Client profile:
- Age: 40-year-old non-smoking Canadian
- Coverage need: Life insurance during key working and family years
- Primary concern: Affordable premiums and sufficient coverage
- Our comparison: We compared term and whole life insurance based on cost, coverage period, cash value, guarantees, and long-term financial needs. For this client, term life insurance was the better fit because affordable coverage for a defined period was the priority.
Why we recommended term life insurance:
- Lower premiums made it possible to get sufficient coverage while staying within budget
- Temporary coverage matched the client’s need to protect their family during their highest financial-responsibility years
- Simple policy structure provided straightforward financial protection without paying for a cash value component they did not need
- Conversion options gave the client flexibility to convert eligible term coverage to permanent insurance later without new medical underwriting, subject to the policy terms
If you are still looking for the best term or whole life insurance policy, speak to a PolicyAdvisor expert to compare and find the best plan for your needs and budget. With PolicyAdvisor, you will receive free instant quotes, the lowest rates in the market, and lifetime after-sales support. Schedule a free consultation today!
Frequently asked questions
Why is term life cheaper than whole life?
Term life insurance policies are generally the most affordable type of coverage when compared to permanent life insurance options like whole life. This is because term policies offer temporary coverage for a set period, without the lifelong protection provided by whole life. They also lack investment components, meaning they don’t build cash value or pay out dividends.
What happens if you outlive term life insurance?
If you outlive your term life insurance policy, coverage typically ends without a death benefit or refund of premiums. Some policies may offer a return-of-premium feature, but these policies usually have higher premiums.
Can I cancel my whole life insurance policy and get money back?
You may be able to surrender a whole life policy and receive its available cash surrender value. The amount you receive can be lower than the premiums you have paid, particularly during the early years of the policy.
Can you convert term life insurance to whole life insurance?
Yes, many term life insurance policies allow you to convert some or all of your coverage to permanent insurance without new medical underwriting. You need to check the policy wording, as the conversion options, deadlines, eligible products, and coverage limits vary by insurer and policy.
How does cash value work in whole life insurance?
In whole life insurance policies, cash value is a savings component that accumulates over time. Each time you pay your premium, a portion is allocated to the cash value, which grows at a specified rate set by the insurer. Over time, it may increase further through earned interest and any dividends paid by the insurer.
The timing of when the cash value becomes accessible depends on the policy type and insurer. Once available, it can be withdrawn, borrowed against, or used as collateral for a loan.
Can whole life insurance premiums increase over time?
Whole life insurance typically has fixed premiums, meaning the scheduled premium does not increase as you age. However, the exact premium structure depends on the policy and payment option you choose.
Which is better for estate planning: term or whole life insurance?
Whole life insurance is generally more suitable for permanent estate-planning needs because it is designed to provide lifelong coverage. It can provide liquidity for final expenses, estate settlement costs, or legacy planning, provided the policy remains in force.
There are some key differences between term and whole life insurance. Term life insurance protects you for a certain number of years. Whole life insurance protects you for your whole life and generates cash value. Term life insurance is usually more affordable, but whole life insurance has value you can access during your lifetime.