 1-888-601-9980

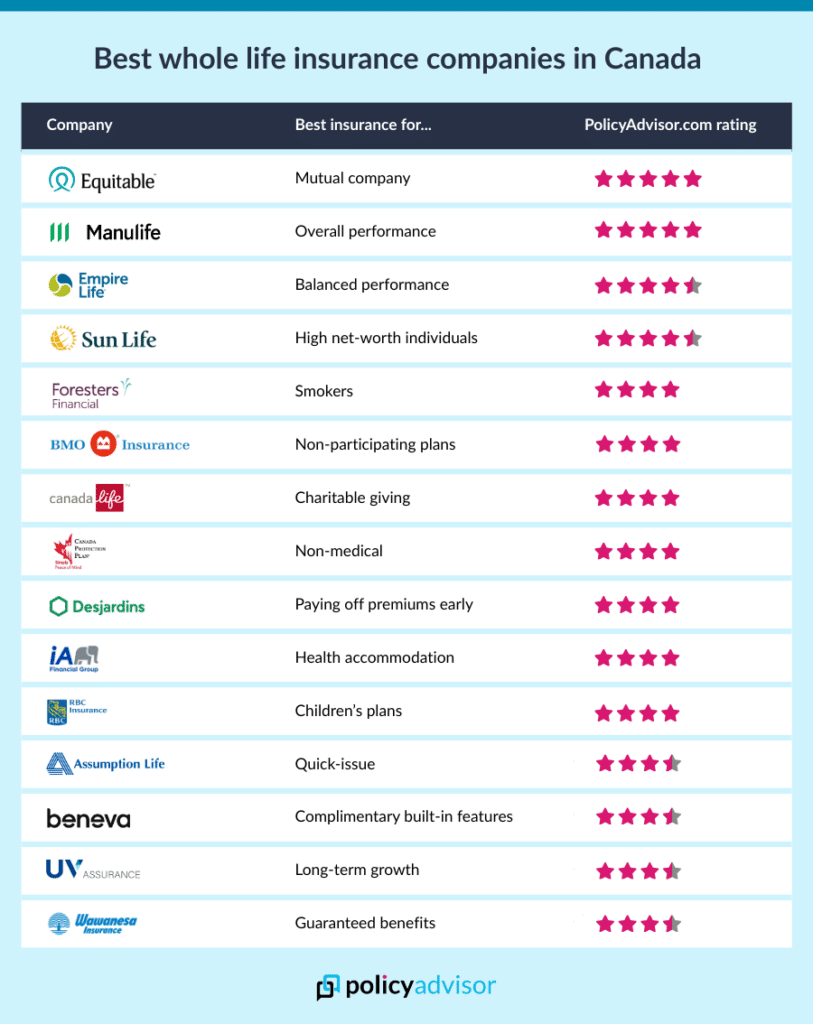
- The best whole life options in Canada for 2026 are Equitable Life, Manulife, Empire Life, Sun Life, and Foresters
- Empire Life stands out for balanced performance, offering steady long-term growth with dependable lifetime guarantees via EstateMax and Optimax
- Equitable Life suits buyers who want a true mutual-company structure, where policyholders share in ownership and value instead of outside shareholders
- Manulife is the best option for Canadians seeking strong overall performance from their whole life insurance
- Foresters Financial is the top pick for smokers due to its competitive rates and its Quit Smoking Incentive
- Sun Life is best suited to high-net-worth buyers, providing large coverage amounts and flexible policy features
Choosing among Canada’s whole life insurers is genuinely difficult: dozens of companies sell participating policies, and each markets strong dividends, long-term cash value growth, and flexible coverage. At PolicyAdvisor, our team compared leading Canadian insurers to determine the best whole life insurance companies across different needs and profiles.
Quick glance
Here are the top 15 whole life insurance companies in Canada that stand out for their combination of strong performance and flexible plans.
| Insurance company | Key strength / Best known for |
| Equitable Life | Mutual company |
| Manulife | Overall performance |
| Empire Life | Balanced performance |
| Sun Life | High-net-worth individuals |
| Foresters | Smokers |
| BMO Insurance | Non-participating plans |
| Canada Life | Charitable giving |
| Canada Protection Plan | Non-medical coverage |
| Desjardins | Early and flexible pay-off |
| iA (Industrial Alliance) | Health accommodation |
| RBC Insurance | Children’s plans |
| Assumption Life | Quick-issue coverage |
| Beneva | Complimentary built-in features |
| UV Insurance | Long-term growth |
| Wawanesa | Guaranteed benefits |
Discover why these companies earned their place in our top 15 below.
Best whole life insurance companies in Canada for 2026
1. Equitable Life: Best for mutual company
Equimax Wealth Accumulator
20-pay
Life-pay
Our advisor’s take:
We give Equitable Life 5/5 because it stands out as one of Canada’s strongest whole life providers, particularly for Canadians who value the long-term security of a true mutual company.
The company supports its participating plans, Equimax Estate Builder and Equimax Wealth Accumulator, with a growing $3.2 billion par fund, demonstrating its financial strength and commitment to stable, long-term results. Both plans offer 10-pay, 20-pay, and Life Pay options.
Equimax Wealth Accumulator is built for earlier cash value access, making it ideal for clients who want flexible liquidity for education, business needs, or retirement planning. Conversely, Equimax Estate Builder emphasizes long-term value and supports estate planning by helping cover taxes and fees at death.
Equimax participating whole life policies include Equitable’s built-in KIND program. It provides compassionate advances (up to 50% of the base coverage amount, maximum $100,000) and snap advances (up to $25,000), a living benefit that gives a lump sum payment from the policy cash value in cases of severe mental or physical disability, and bereavement counselling benefits (up to $1,000).
Equitable Life’s key financial strengths:
- $3.2 billion participating fund
- 6.40% dividend scale interest rate, held above 6% for more than 12 consecutive years
- 30-year average return of 7.35% to 7.72%
- Very low volatility. A 1.74% standard deviation over 30 years, among the steadiest in Canada
- Par fund asset mix: 49% fixed income, 38% non-fixed income, 2% cash, 11% policy loans
Why choose Equitable Life
- Stable long-term returns with low volatility
- A diversified par-fund portfolio supporting long-term growth
- Participating policyholders can share in the earnings of the participating account through dividends
- Conservative, disciplined fund management
Unique selling point (USP): Equimax Estate Builder and Equimax Wealth Accumulator suit buyers who want stable long-term value, potential dividends, and accessible cash value from a trusted mutual insurer.
Equimax Estate Builder: Slower early growth; strong long-term value
Equimax Wealth Accumulator: Faster early growth; accessible sooner
Paid-up additions (PUA), enhanced protection, cash, premium reduction, and on deposit
2. Manulife: Best for overall performance
Manulife Par with Vitality Plus
20-pay
pay-to-90
pay-to-100
Our advisor’s take:
Manulife earns a 5/5 as the strongest all-around pick for buyers who want capital strength, global diversification, and disciplined risk management behind their policy.
Manulife Par and Manulife Par with Vitality Plus plans provide lifetime coverage with 10-pay, 20-pay, Pay to Age 90, and Pay to Age 100 options. A multi billion dollar participating account backs the plans, supporting long-term guarantees, stable dividends, and reliable performance for policyholders.
Manulife Par focuses on stable long-term growth with guaranteed premiums, immediate cash value buildup, and annual dividend payouts. Manulife Par with Vitality Plus offers strong early guaranteed cash values while also providing access to the Manulife Vitality program, which rewards healthy living with perks and member benefits.
Program features vary by eligibility and do not reduce premiums for participating whole life, but achieving higher Vitality status (like Gold or Platinum) can result in an additional Vitality Dividend.
Manulife’s key financial strengths and performance:
- Multi‑billion‑dollar participating account
- 6.35% dividend scale interest rate
- 136% LICAT ratio, among the highest capital-strength levels in Canada
- Diversified global operations across Canada, the U.S., and Asia
- Global operations spanning Canada, the U.S., Asia, and asset management
- Strong balance sheet supported by investment-grade assets
- Disciplined risk-management framework supporting long-term stability
Why choose Manulife
- Exceptionally strong capitalization supports long-term dividend stability
- Global diversification reduces performance volatility
- Consistent profitability from core earnings and disciplined risk management
- Vitality wellness program and underwriting analytics add ongoing value
Unique selling point (USP): Manulife Par and Manulife Par with Vitality Plus, suit buyers who want affordable lifetime coverage, flexible payment terms, and steady cash value.
Manulife Par: Cash value starts after 1 year (for most age and payment structures)
Manulife Par with Vitality Plus: Cash value begins after year 1; includes Vitality benefits
Paid-up additions (PUA), term additions (enhanced coverage), cash, premium reduction, and dividends on deposit
3. Empire Life: Best for balanced performance
Optimax Wealth (plus non-participating Solution Series)
10-pay
20-pay
Life-pay (varies by plan)
Our advisor’s take:
We give Empire Life 4.5/5 because its whole life plans offer balanced, steady performance, making it a top choice for Canadians seeking reliable long-term value. The company backs its participating plans, EstateMax and Optimax Wealth, with a disciplined $1.32 billion par fund renowned for stability and long-term results.
EstateMax focuses on estate growth, offering steady dividend performance and strong long-term accumulation. In comparison, Optimax Wealth provides stronger early cash value accumulation.
Optimax Wealth offers 8 Pay, 10 Pay, 20 Pay and Life Pay to age 100 options, while EstateMax offers 10 Pay, 20 Pay and Life Pay options. Empire Life also offers the Solution Series, which includes a permanent non-participating plan called Solution 100 with level premiums payable to age 100.
Empire Life’s key financial strengths:
- $1.32 billion participating fund
- 6.25% dividend rate
- 30-year average return of 6.97%
- Par fund asset mix: 64% bonds, 37% in commercial mortgages, equities, and cash
- A long-duration bond structure with smoothing to reduce volatility
Why choose Empire Life:
- Stable historical participating account returns with relatively low volatility
- A consistent dividend track record that supports confident planning
- Solid cash-value access over time
- Well suited to conservative estate planning
Unique selling point (USP): EstateMax and Optimax Wealth suit buyers who want steady cash accumulation and consistent dividend performance.
EstateMax: Focuses on steady long-term growth and estate planning
Optimax Wealth: Focuses on higher early cash value accumulation
Paid-up additions (PUA), enhanced coverage, cash payment, annual premium reduction, and cash accumulation (deposit)
4. Sun Life: Best for high-net-worth individuals
Sun Par Accumulator II
SunSpectrum Permanent Life II
20-pay
Life Pay (varies by plan)
Our advisor’s take:
We give Sun Life 4.5/5 for being a leading choice for high-net-worth Canadians who want whole life insurance backed by exceptional global diversification and long-term financial strength. Sun Life backs its Par Protector II, Par Accumulator II, and Par Accelerator with a $21.2 billion par fund. This fund supports more than 400,000 active participating policies, making it one of the strongest par structures in Canada.
The Protector II and Accumulator II provide flexible payment options, including Life Pay, 10-pay, and 20-pay, while Accumulator II emphasizes early cash-value growth, allowing easier access to funds for investments, business needs, or other financial goals through policy loans or withdrawals.
Meanwhile, Sun Par Protector II focuses on maximizing long-term death benefit growth for estate and legacy planning. SunSpectrum Permanent Life II also offers Life Pay, 10-pay, and 20-pay payment structures.
Sun Life’s key financial strength
- $21.2 billion participating account backing 400,000+ active policies
- 6.25% dividend scale interest rate
- 145% LICAT ratio, among the strongest of the major Canadian insurers
- Earnings diversified across Canada, the U.S., and Asia
- Consistent profitability from both insurance and wealth-management operations
Why choose Sun Life
- Global diversification supports long-term performance stability
- Exceptional capital strength backs long-term guarantees
- Participating whole life options designed for both estate planning and cash value accumulation
- Strong fit for affluent and corporate tax-efficient planning
Unique selling point (USP): Sun Par Protector II, and Sun Par Accumulator II suit buyers who want lifetime protection paired with strong cash-value potential and estate-planning power.
Sun Par Protector II: Cash value begins after year 5
Sun Par Accumulator II: Cash value begins after year 1
Paid-up additions (PUA), enhanced insurance, cash payment, annual premium reduction, and dividends on deposit
5. Foresters Financial: Best for smokers
Advantage Max
Non-Par Whole Life
20-pay
pay-to-100
Our advisor’s take:
We give Foresters Financial 4/5 for being a top choice for smokers and former smokers, who need more flexible underwriting. The insurer leverages a strong Canadian capital position, including a Life Insurance Capital Adequacy Test (LICAT) ratio of 188% and $2.3 billion in surplus. This robust financial strength enables Foresters to accept higher-risk applicants while actively maintaining dependable long-term guarantees and stable dividends.
Advantage Plus offers early cash value accessibility, dependable long-term guarantees, and dividend-driven growth, making it an attractive option for Canadians who may face stricter underwriting at larger insurers. Foresters also offer permanent plans that feature guaranteed cash values. Advantage Max offers coverage from $50,000 to $20,000,000 and 10-Pay, 20-Pay and Pay to 100 premium payment plans.
Foresters’ key financial strengths:
- 188% LICAT ratio, indicating excellent capital adequacy
- $2.3 billion in surplus / net assets
- Member-owned (fraternal) structure
Why choose Foresters:
- Flexible underwriting for smokers and former smokers
- Strong financial resilience backing long-term guarantees
- A member-first model that directs value back to policyholders
- Added perks: wellness rewards, scholarships, community grants, family support programs
Unique selling point (USP): Advantage Max is a strong fit for smokers due to its quit smoking incentive plan.
Advantage Plus II: Cash value begins after year 1
Foresters Non-Par Whole Life: Guaranteed cash values; slower growth
Advantage Max: Guaranteed cash value with an option to purchase more paid-up insurance
Paid-up additions (PUA), dividends on deposit, cash payment, enhanced insurance, and annual premium reduction
6. BMO: Best for non-participating whole life insurance
Wealth Accelerator
20-pay
pay-to-100
Our advisor’s take:
BMO is a 4/5 for buyers who want guaranteed values and predictable premiums without dividend-related ups and downs. The company offers two plan options, Estate Protector and Wealth Accelerator, both of which exclude a participating account or dividends. These plans set themselves apart with a Performance Bonus (6.00% effective for the 2026/2027 period, updated from 5.75%), increasing both the death benefit and cash value without relying on traditional dividends.
Estate Protector is designed for long-term estate planning, offering strong guaranteed cash value growth and a steadily increasing death benefit to help preserve wealth and offset taxes at death (e.g., deemed disposition and probate fees). Wealth Accelerator provides faster guaranteed cash value accumulation and higher early liquidity, making it an attractive option for business owners and high-income earners who want accessible long-term value. Both plans are available with 10-pay, 20-pay, and pay to 100 premium options.
BMO’s key financial strengths
- $88 million in net insurance income for Q3 2026
- 6% performance bonus, enhancing both the death benefit and cash value
- Backed by BMO Wealth Management’s broader risk management and diversified earnings
Why choose BMO
- Consistently growing insurance profitability
- A competitive guaranteed bonus rate strengthens policy values
- Diversified revenue sources add stability
- Benefits from BMO’s operational scale and risk oversight
Unique selling point (USP): Estate Protector and Wealth Accelerator suit buyers who want lifetime coverage with guaranteed values and additional growth through the performance
Estate Protector: Strong guaranteed values; long-term estate growth
Wealth Accelerator: Faster liquidity; quicker cash-value access
Not applicable. A performance bonus purchases paid-up additions instead of a traditional dividend
7. Canada Life: Best for charitable giving
Wealth Achiever
Balanced Achiever
My Par Gift
20-pay
pay-to-100
Our advisor’s take:
We give Canada Life 4/5 for being the leading choice for buyers who want to structure their whole life around charitable giving. Its My Par Gift plan is specifically designed for charitable contributions, with a single premium and cash value building in the early years.
Canada Life’s participating lineup, Estate Achiever, Wealth Achiever, Balanced Achiever, and My Par Gift, is backed by one of the largest and most stable participating accounts in the country. It’s anchored by a $61.9 billion par fund, the largest in Canada.
Estate Select focuses on long-term growth, helping maximize the death benefit for estate planning. Wealth Select, on the other hand, is designed for earlier cash value access, allowing for withdrawals or policy loans when needed. Both plans come with flexible payment options, including 10-pay, 20-pay, and pay to 100, while My Par Gift requires a single premium.
Canada Life’s key financial strengths
- $62.8 billion participating fund (the largest in Canada) backing roughly 1.4 million in-force policies
- 6.00% Dividend Scale Interest Rate
- Formal governance covering liability matching, liquidity, tax considerations, and interest-rate risk
- Cash-flow-matched asset-liability management
- Asset mix: 60.5% fixed income, 30.5% non-fixed income (real estate, public and private equity)
Why choose Canada Life
- Deep diversification and scale support exceptional long-term stability
- A balanced asset mix aims for steady returns across market cycles
- Disciplined asset-liability management reduces volatility
- Strict governance protects long-term policyholder value
Unique selling point (USP): My Par Gift suits buyers who want charitable giving handled through single-premium simplicity.
Estate Achiever: Cash value starts in year 1, with a focus on long-term growth and maximizing the death benefit for estate planning
Wealth Achiever:Cash value from year 1; earlier access via withdrawals or loans
Balanced Achiever: Cash value from year 1; earlier access via withdrawals or loans
My Par Gift: Builds over time; accessible to the designated charity
Paid-up additions (PUA), enhanced coverage, cash payment, annual premium reduction, and dividends on deposit
8. Canada Protection Plan: Best for non-medical whole life insurance
Preferred Elite
Simplified Elite
Deferred Life
Guaranteed Acceptance Life
Deferred
Deferred Life
Life-pay
Our advisor’s take:
We give Canada Protection Plan (CPP) 4/5 for being a leading choice for Canadians who want life insurance without medical exams, offering fast approvals and guaranteed lifetime coverage. Its lineup of non-participating permanent and term plans, including Express Elite (Term), Simplified Elite, Guaranteed Acceptance Life, and Deferred Life, provides predictable premiums, stable cash values, and simplified underwriting for applicants with various health profiles. As part of Foresters Financial, Canada Protection Plan is backed by a Life Insurance Capital Adequacy Test (LICAT) ratio of 188% and consolidated surplus of $2.3 billion, giving policyholders confidence in the company’s long-term financial strength and the security of their coverage.
A 4/5 as the top pick for buyers who want whole life coverage without a medical exam, with fast approvals and guaranteed-acceptance options. CPP operates as part of Foresters Financial.
Canada Protection Plan’s key financial strengths:
- Backed by parent company Foresters Financial: 188% LICAT ratio and $2.3 billion consolidated surplus
- $662 million in claims paid in 2025 in North America
- A member-focused structure that reinvests surplus into member programs, scholarships, and community support
Why choose Canada Protection Plan
- Canada’s largest provider of no-medical life insurance
- Accepts a wide range of health profiles, including smokers and higher-risk applicants
- Guaranteed, non-participating pricing with no dividend risk
- Higher maximum issue ages and a Quit Smoking incentive
- Fast digital application process with e-signatures
Unique selling point (USP): CPP is the strongest fit for buyers who want no-medical whole life with fast approval and guaranteed lifetime coverage.
Across the plan lineup: Cash values on Guaranteed Acceptance, Deferred, Deferred Elite, Simplified Elite, Preferred, and Preferred Elite generally begin at after policy year 5
None
9. Desjardins: Best for early and flexible pay-off
Estate Enhancer
Accelerated Growth
10-pay
20-pay
pay-to-100 (varies by plan)
Our advisor’s take:
Desjardins is a 4/5 for buyers who want to pay off a whole life policy quickly. It is one of the only insurers offering a genuine 5-pay participating option alongside the standard 10-pay, 20-pay, pay to 100 structures across its par lines.
The company backs its participating lineup with one of the strongest capital positions in Canada, maintaining a Tier 1A capital ratio of 23.2% (as of Q1 2026).
The flagship 5-Pay PAR plan completes premiums in just five years while still building strong early cash values. Desjardins serves millions of members and clients across its extensive cooperative financial and insurance portfolio.
Its participating lineup includes three plans: 5-Pay PAR, Estate Enhancer, and Accelerated Growth. Estate Enhancer focuses on long-term estate value and strong future growth, while Accelerated Growth prioritizes earlier cash value access with long-term accumulation potential.
Desjardins’ key financial strengths and performance
- 6.30% Dividend Scale Interest Rate (DSIR)
- 23.2% Tier 1A capital ratio, well above regulatory requirements
- $3.81 billion in annual surplus earnings and $960 million in Q1 2026 surplus earnings before member dividends
- Millions of policyholders across its life and health portfolio
- A co-operative ownership model that reinvests profit into members
Why choose Desjardins
- One of the only 5-pay participating whole life plans in Canada
- Co-operative structure reinvests profit into member value
- Strong capital ratios safeguard dividend durability
- A flexible product range spanning fast-pay to long-term accumulation designs
Unique selling point (USP): The 5-Pay PAR plan delivers fully paid-up coverage in five years while still building early cash value.
5-Pay PAR: Steady long-term growth
Estate Enhancer: Steady long-term growth
Accelerated Growth: Fastest cash-value access, concentrated in years 10–15
5-Pay PAR: Enhanced insurance
Estate Enhancer and Accelerated Growth: Paid-up additions (PUA), annual premium reduction, cash payment, deposits at interest, and enhanced insurance
10. Industrial Alliance (iA): Best for health accommodation
iA PAR Estate
iA PAR Wealth
Life and Serenity 65
20-pay
pay-to-100
Our advisor’s take:
A 4/5 for who need whole life insurance with more flexible underwriting, making it especially appealing for clients with health conditions or non-standard risk profiles.
iA also offers Canadians whole life solutions for different needs: Child Life and Health Duo combines life and critical illness coverage for children and provides non participating coverage with early protection and gradual long-term growth, while Life and Serenity 65 delivers non-participating coverage with disability and illness benefits, with cash values beginning in later policy years.
Additionally, iA PAR Estate and iA PAR Wealth are backed by a $330 million par account and offer flexible premium options, including 10-pay, 20-pay, and pay to 100. iA PAR Estate focuses on long-term growth of total surrender value and death benefit, while iA PAR Wealth prioritizes short-term growth by maximizing total cash surrender value in the early years, alongside long-term estate growth.
iA’s key financial strengths
- $330 million participating fund
- 15.1% return on equity (17.5% core ROE)
- 137% solvency ratio
- A diversified business spanning Individual Insurance, Group Benefits, Wealth, and U.S. operations
Why choose Industrial Alliance (iA)
- Delivers strong and growing earnings, contributions broadly across Individual Insurance, Wealth, Group, and U.S. operations
- Supports reduced volatility with a highly diversified business model and multiple profit streams beyond life insurance
- Demonstrates robust financial strength, boasting a 132% solvency ratio and strong organic capital generation that sustains long-term par stability
- Leads market position, ranks number one in segregated fund sales and strong momentum in Individual Insurance
- Consistently generates profitability, reflected in a 16.1% core ROE, demonstrating durable earning power for sustaining long-term guarantees
- Strategically expands through acquisitions, which strengthens distribution and recurring revenue sources
Unique selling point (USP): iA PAR Estate and iA PAR Wealth suit buyers with health conditions who need underwriting flexibility.
Child Life and Health Duo: Gradual long-term growth with early protection
iA PAR Estate: Long-term cash value accumulation
iA PAR Wealth: Early access to cash value
Life and Serenity 65: Cash values begin in later policy years
Paid-up additions, premium reduction, cash, deposit with interest (Child Life and Health Duo, iA PAR Estate, iA PAR Wealth)
11. RBC Insurance: Best for children’s plans
RBC Growth Insurance Plus
20-pay
pay-to-100
Our advisor’s take:
We give RBC Insurance 4/5 as the top choice in Canada for families who want whole life insurance designed specifically to protect a child’s long-term future. RBC backs its participating plans, Growth Insurance and Growth Insurance Plus, with a growing participating account backed by RBC’s institutional strength. Both plans feature the Juvenile Guaranteed Insurability Benefit, which lets a child buy additional coverage later without a medical exam.
Growth Insurance focuses on tax-deferred accumulation and a steadily increasing death benefit, making it ideal for long-term family legacy planning. Growth Insurance Plus accelerates cash value access with cash values accessible after the first policy year, giving families greater flexibility for education, investment opportunities, or liquidity needs through policy loans or collateral.
Growth Insurance focuses on tax-deferred accumulation and a steadily increasing death benefit, making it ideal for long-term family legacy planning. Growth Insurance Plus accelerates cash value access, giving families greater flexibility for education, investment opportunities, or liquidity needs through policy loans or collateral.
RBC’s key financial strengths
- $51.39 million participating fund
- 6.30% dividend rate (officially maintained for the April 1, 2025 to March 31, 2026 period)
- Stable long-term DSIR history
- Serves more than 5 million clients across diversified segments
- A 50/50 target asset mix between fixed income and non-fixed income (including commercial real estate)
Why choose RBC
- Smoothing techniques help stabilize returns and support consistent dividends
- Scale across a large client base supports long-term stability
- A balanced 50/50 allocation aligns growth with risk control
- Disciplined oversight aims to maximize policyholder value
Unique selling point (USP): RBC Growth Insurance and Growth Insurance Plus suit families who want guaranteed cash values, long-term growth, and early access to funds when needed.
RBC Growth Insurance: Cash values accessible after policy year 5
RBC Growth Insurance Plus: Faster early cash value accumulation with liquidity accessible after year 1
Paid-up additions (PUA), cash payments, reduced premiums, interest-earning deposits, and enhanced insurance
12. Assumption Life: Best for quick-issue policies
ParPlus Junior
Non Par (Golden Protection, Platinum Protection, Silver Protection, Bronze Protection)
pay-to-100
Our advisor’s take:
We give Assumption Life 3.5/5 for offering some of Canada’s strongest fast-approval permanent insurance options, making it an excellent fit for clients who want lifetime coverage without medical exams or long underwriting queues. Backed by a 167% solvency ratio and more than 120 years as a Canadian mutual insurer, Assumption Life provides a highly stable foundation for its quick-issue non-participating including Golden Protection, Platinum Protection, etc).
These plans pair simplified, primarily digital applications with streamlined underwriting and rapid decisions, and are available with flexible payment options such as pay to 100 and select limited-pay structures, giving clients guaranteed premiums, level lifetime coverage, and predictable long-term costs.
Assumption Life’s key financial strengths:
- 5.75% dividend rate (applicable to their ParPlus participating line, as Golden Protection and FlexOptions are non-par/universal life products)
- 167% solvency ratio
- $12 million in net earnings
- $2.6 billion in total assets
- $212 million in policyholder’s equity
- Mutual ownership structure
Why choose Assumption Life:
- A mutual model that prioritizes long-term policyholder value
- High surplus and solvency levels back long-term guarantees
- A largely digital, streamlined underwriting and application process
- Disciplined balance between growth and risk
- Simplicity and speed for buyers who want guaranteed, no-exam coverage
Unique selling point (USP): Assumption Life is the strongest fit for fast approvals and simplified underwriting on guaranteed, no-exam whole life.
ParPlus: Dividend‑based cash accumulation with guaranteed cash values
ParPlus Junior: Guaranteed cash value growth plus annual dividends
Platinum Protection Whole Life: Guaranteed cash surrender values beginning after year 5
Golden Protection Whole Life: Guaranteed cash values with steady growth
Silver Protection: Guaranteed cash values with gradual buildup
Bronze Protection: Guaranteed cash values with graded accumulation
Paid-up additions, enhanced coverage, cash, premium reduction, and deposits at interest
13. Beneva: Best for complementary additional features
Whole Life Superior Value 100
Enhanced Term 100
20-pay
pay-to-100
PolicyAdvisor Rating
We give Beneva 3.5/5 for being an excellent choice for Canadians who want non participating whole life insurance. Beneva is a mutual company, which often aligns with participating policies, but mutual status alone doesn’t guarantee a par product exists. In Beneva’s case, their whole life line is structured as non‑par, with value delivered via builtin features and cash values rather than dividends.
Supported by a $29.2 billion asset base and a 163% solvency ratio, Beneva’s whole life plan offers lifetime protection with complimentary benefits designed to enhance coverage, service, and long-term value.
Beneva’s key financial strengths:
- $29.2 billion in total assets
- $673.8 million in consolidated net income
- 14.9% return on equity
- $4.9 billion in consolidated equity
- 163% solvency ratio
Why choose Beneva
- A mutual, member-first model that reinvests profit into members
- A large asset base supporting long-term financial stability
- Strong ratings and governance behind its claims-paying credibility
- Bundled benefits that add value without extra rider costs
Unique selling point (USP): As Canada’s largest mutual insurer, Beneva reinvests profit into member benefits and product improvements rather than shareholder returns.
Beneva Participating Whole Life: Cash values available in later years
Beneva Non-Participating Whole Life: Guaranteed cash value
None
14. UV Insurance: Best for long-term growth
Adaptable Whole Life
Whole Life Pay to 100
20-pay
8-pay
pay-to-100 (varies by plan)
Our advisor’s take:
We give UV Insurance 3.5/5 for being an excellent choice for Canadians who want long-term, reliable whole life growth backed by a mutual company with over 135 years of operations. Supported by a strong 172% solvency ratio, UV delivers the kind of financial stability that long-term policyholders depend on. Its non-participating whole life plans focus on steady, predictable cash value accumulation with conservative investment management and policyholder-first governance.
UV Insurance’s key financial strengths
- 135+ years as a mutual insurer, operating under a policyholder-owned structure
- $7.9 million in net income for 2025
- 172% solvency ratio
- $281.3 million in mutual members’ equity as of 2025
- A fully digital underwriting platform (My Universe)
Why choose UV Insurance
- Reinvests profit into members rather than external shareholders
- A high solvency ratio protects long-term guarantees
- A digital-first underwriting and application experience
- Directs more than 10% of profits to health, education, and social initiatives
- Over a century of mutual-model stewardship
Unique selling point (USP): UV prioritizes long-term growth with high cash-value potential (up to 50% of the coverage amount by age 65 in select plans) plus digital simplicity.
Whole Life High Values: High long-term growth; cash values can reach up to 50% of the coverage amount by age 65 or after 20 payments for those aged 46 and older
Adaptable Whole Life: Cash value begins in later policy years; high surrender values available from the 10th policy anniversary
Non‑participating whole life (Whole Life Pay to 100) : Cash value begins from the 5th contract anniversary
Not applicable as UV primarily offers a non-participating lineup
15. Wawanesa: Best for value and guaranteed benefits
Whole Life Pay to Age 100
pay-to-100
Our advisor’s take:
We give Wawanesa 3.5 / 5 for being a leading choice for Canadians who want whole life insurance with dependable guarantees, conservative investment management, and long-term affordability. The Wawanesa Life Par offering provides both 20-Pay and Pay to Age 100 premium options. Wawanesa backs this participating plan with a strong financial foundation, including solid capital backing across its life division. The plan delivers predictable, steady cash value growth and consistent dividend performance, supported by a disciplined bond-focused investment strategy.
Wawanesa’s key financial strengths
- 6.00% Dividend Scale Interest Rate (DSIR)
- $1.9 billion life insurance asset base
- $4.7 billion in group equity / surplus supporting the wider mutual group
- $311 million in life division equity
Why choose Wawanesa:
- Conservative asset management supports dependable dividend performance
- A high-quality, low-volatility bond portfolio limits swings
- Strong surplus reserves from a leading Canadian mutual insurer
- Profits flow to policyholders rather than shareholders
- Competitive, affordable pricing with reliable guarantees
Unique selling point (USP): Wawanesa Life Par delivers predictable, steady cash-value growth and consistent dividend performance through a disciplined, bond-focused strategy.
Wawanesa Life Par: Guaranteed cash values; dividend-eligible (with cash values typically beginning as early as policy year 5)
Paid-up additions (PUA), annual premium reduction, cash payment, or accumulation at interest (left on deposit)
Methodology: How we determined the best whole life insurance companies in Canada
We selected the best whole life insurance companies in Canada by evaluating the following:
- Financial Strength & Metrics: LICAT ratios, par fund sizes, surplus, solvency ratios, and net income figures.
- Dividend Scale Interest Rates (DSIR): Current board-approved rates (e.g., 6.40% for Equitable, 6.00% for Canada Life, etc.) and their active dates.
- Policy Details & Payment Options: Exact premium payment terms (10-pay, 20-pay, Pay to Age 100, Life Pay) and product types.
- Cash Accumulation Timelines: Whether cash value starts in year 1, year 5, or later.
- Dividend Options: Available payout choices like Paid-up Additions (PUAs), cash payments, and deposits at interest.
- Underwriting Flexibility: Specializations such as no-medical/simplified issue, smoker-friendly programs, and alignment with estate, juvenile, or high-net-worth planning.
Cost of whole life insurance in Canada
Whole life insurance costs vary by age, health, coverage amount, plan type, and payment term. Younger applicants and non-smokers get lower premiums; higher death benefits and shorter payment terms (e.g., 10-pay) raise the annual cost.
Illustrative cost of $100,000 whole life insurance by insurer
| Insurer | Annual premium | Cash value: year 20 | Cash value: year 40 | Death benefit: year 40 |
| BMO | $1,230 | $21,482 | $116,483 | $246,237 |
| Canada Life | $800 | $13,419 | $68,267 | $121,507 |
| Empire Life | $689 | $14,574 | $67,845 | $132,540 |
| Equitable Life | $818 | $21,481 | $90,510 | $163,023 |
Figures illustrate a $100,000 life-pay participating whole life policy for a healthy 30-year-old female non-smoker. Cash values and death benefits are not guaranteed and depend on dividends, insurer performance, and policy design; actual premiums and results vary by underwriting and product options.
How to choose the best whole life insurance in Canada
Choosing the best whole life insurance policy comes down to comparing costs, features, flexibility, and the insurer’s financial strength. Here are the key factors to review before you decide:
- Premiums and charges: Compare premium levels across companies and check for extra fees such as admin charges or rider costs
- Customer support: Look for strong service ratings, easy policy management, and responsive support
- Claims handling: Favor insurers known for fast, low-friction claims during critical times
- Policy flexibility: Prioritize plans with useful riders and customization so coverage can be tailored
- Underwriting requirements: Weigh medical-exam vs. no-exam trade-offs — no-exam is more convenient but may cost more
- Company standing: Check financial strength ratings and long-term performance for stability and reliability
Licensed PolicyAdvisor advisors will help you compare options, answer questions, and ensure your coverage aligns with long-term goals.
Frequently Asked Questions
Learn about the best whole life insurance companies in Canada. We’ve used our years of experience and careful research to create our list of the 15 best whole life insurance companies in Canada to help you choose a provider that fits your family’s needs. Many top insurers made the list, but we evaluated more than size and popularity. Read our reviews to see what we ranked each company “best for.”