 1-888-601-9980

- Top Super Visa insurance providers in 2026 include Allianz, TuGo, Manulife, Destination Canada, GMS, 21st Century, and Secure Travel (RIMI)
- To be approved, your policy must provide a minimum of $100,000 CAD in emergency coverage, include hospitalization and repatriation, and be valid for at least one year from the date of entry
- Premiums are primarily determined by the applicant's age, chosen coverage limits, and any stable pre-existing medical conditions
- Beyond fulfilling visa requirements, this specialized insurance protects visiting parents and grandparents from the high out-of-pocket costs of Canadian healthcare during extended stays
Planning to bring your parents or grandparents to Canada? While the Super Visa program makes long-term family reunions easier, securing the right Super Visa medical insurance is a mandatory first step. This specialized visitor-to-Canada insurance protects extended-stay visitors by covering emergency medical care, hospital stays, and prescription medications.
Choosing the right plan isn’t just about checking a box for Immigration, Refugees and Citizenship Canada (IRCC); it is about protecting your family from unexpected financial burdens while ensuring they receive the best possible care. In this guide, we have reviewed the best Super Visa insurance providers in Canada.
Top five Super Visa insurance providers in Canada:
- Allianz: Best for frequent travellers
- TuGo: Best for customizable riders
- Manulife: Best for value-added services
- Destination Canada: Best for comprehensive coverage
- Group Medical Services (GMS): Best for competitive pricing
How much does Visitor Insurance cost?
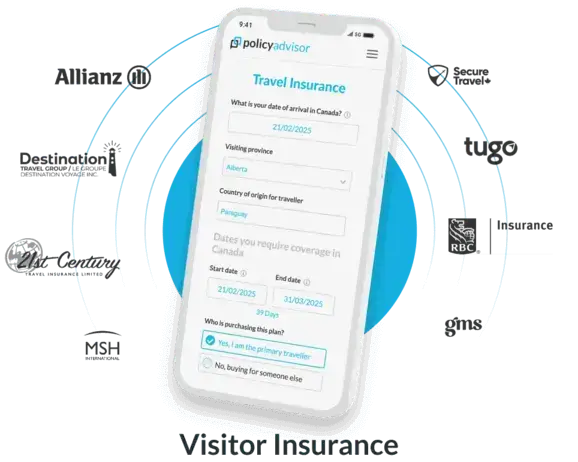
Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.
Powered by

What is Super Visa insurance in Canada?
Super Visa insurance is mandatory travel medical insurance for parents and grandparents of Canadian citizens or permanent residents applying for a Super Visa.
Because visitors are not eligible for Canada’s provincial healthcare systems, this specialized insurance protects them from the high out-of-pocket costs of emergency medical care. Successfully securing this policy is a prerequisite for the visa, which allows eligible family members to stay in Canada for up to five consecutive years per entry without needing to renew their status.
Official IRCC Super Visa insurance requirements (2026)
- Minimum $100,000 coverage for health care, hospitalization, and repatriation
- Valid for at least one year from entry into Canada
- Covers health care, hospitalization, and repatriation
- Paid in full before application (monthly plans only qualify if the insurer has received full payment and can issue proof)
- From a Canadian insurer or an OSFI‑authorized foreign insurer on IRCC’s designated list
Best Super Visa insurance companies in Canada (2026)
We ranked the best Super Visa insurance companies in Canada for 2026 based on cost, coverage flexibility, pre-existing condition support, and customer experience. These plans meet IRCC requirements and protect visitors during long stays.
- Allianz: Best for frequent travellers
- TuGo: Best for customizable riders
- Manulife: Best for value-added services
- Secure Travel (RIMI): Best for senior travellers
- Destination Canada: Best for comprehensive coverage
- GMS (Group Medical Services): Best for competitive pricing
- 21st Century: Best for healthy travellers
Let’s take a closer look at each of these top insurers, their unique features, and what makes them stand out in 2026.
Detailed reviews of the best super visa insurance companies in Canada (2026)
According to our licensed insurance experts, the providers below are among the best super visa insurance companies in Canada for 2026.
1. Allianz: Best for frequent travellers
PolicyAdvisor rating
We rate Allianz 5/5 because it perfectly balances medical coverage with strong international service capabilities. It is our top recommendation for parents and grandparents who travel frequently, take side trips outside of Canada, or split their time between multiple countries.
Their policy provides 24/7 multilingual emergency assistance and highly efficient global claims coordination. Additionally, their Super Visa plans include built-in travel benefits (like Accidental Death & Dismemberment) alongside standard emergency medical coverage, making it ideal for visitors seeking robust, all-in-one protection.
Why choose Allianz
- Strong global claims network and international assistance infrastructure
- 24/7 multilingual emergency support
- Includes built-in travel benefits beyond emergency medical coverage
- Options available up to $500,000 CAD for maximum peace of mind
Unique selling point (USP): Allianz offers multilingual emergency assistance, strong international claims support, and select travel-related benefits alongside IRCC-compliant medical coverage, depending on the plan version.
2. TuGo: Best for customizable riders
PolicyAdvisor rating
We rate TuGo 5/5 because it offers more deep customization than almost any other provider on the market.
TuGo’s Super Visa insurance is ideal for families who need protection tailored to specific medical or travel risks rather than a rigid, standard plan. While they offer standard coverage for pre-existing medical conditions that meet age-based stability periods, their standout feature is the optional 7-day stability rider. This unique add-on allows applicants with recently fluctuating or “unstable” conditions to get coverage, drastically reducing the standard 90-to-180-day waiting period to just 7 days.
Why choose TuGo
- One of the most flexible Super Visa insurance plans in Canada
- Optional riders for unstable pre-existing conditions
- Coverage options extend beyond basic emergency medical care
- Range of deductible options (from $0 up to $10,000)
Unique selling point (USP): TuGo offers high coverage limits and customizable riders, including options for unstable pre-existing conditions and travel-related risks, under an IRCC-compliant plan.
3. Manulife: Best for value-added services
PolicyAdvisor rating
We give Manulife 5/5 because it seamlessly combines essential medical coverage with a suite of premium, value-added benefits.
As one of Canada’s largest and most trusted financial institutions, Manulife offers Super Visa applicants three distinct tiers of coverage (Basic, Standard, and Enhanced). Beyond standard hospital care, Manulife stands out by bundling practical extras into their policies such as emergency prescription drug coverage, accidental dental treatment, and companion support benefits, making it a reliable choice for families seeking complete, holistic protection.
Why choose Manulife
- Includes prescription drug coverage, accidental dental, and companion benefits
- Flexible plan options for applicants with or without pre-existing conditions
- Strong financial backing and national recognition
- Allows for brief side trips outside of Canada (excluding the applicant’s home country)
Unique selling point (USP): Manulife provides comprehensive medical coverage with added benefits such as prescription drugs, accidental dental, and companion support, all under an IRCC-compliant plan.
4. Secure Travel (RIMI): Best for senior travellers
PolicyAdvisor rating
We give Secure Travel (RIMI) 4.5/5 because it provides one of the most affordable and accessible options on the market, specifically tailored for senior applicants aged 60 and above.
Underwritten by the iA Financial Group, Secure Travel allows families to choose between two straightforward plan tiers: one that excludes pre-existing conditions to keep costs low, and one that includes them. For Super Visa applicants, their biggest advantage is the monthly payment option. Instead of paying thousands of dollars upfront, one can manage the cost of mandatory IRCC medical insurance through affordable monthly installments.
Why choose Secure Travel (RIMI)
- Optional coverage for stable pre-existing conditions
- Affordable premiums designed for senior travellers
- Monthly payments help manage upfront costs
- Provides coverage for senior applicants up to 90 years of age
- Offers coverage ceilings up to $1,000,000 CAD
Unique selling point (USP): Secure Travel (RIMI) delivers budget-friendly emergency medical coverage with optional pre-existing condition protection, meeting IRCC requirements for seniors.
5. Destination Canada: Best for comprehensive coverage
PolicyAdvisor rating
We give Destination Canada 4/5 because it offers one of the most robust, feature-rich policies available for older travellers. The plan is highly competitive for applicants in their 70s. Families can customize their coverage by including or excluding stable pre-existing conditions.
Notably, their 120-day stability requirement for applicants up to age 79 is more forgiving than the 180-day window required by many competitors. Additionally, Destination Canada is one of the few approved providers that actively supports monthly payment plans, allowing Canadian sponsors to pay a standard two-month deposit rather than financing the entire year upfront.
Why choose Destination Canada
- Strong add-ons such as AD&D, accidental dental, follow-up care, and companion coverage, with availability and limits varying by plan version
- Allows inclusion or exclusion of stable pre-existing condition coverage
- Supports monthly premium payments for greater financial flexibility
Unique selling point (USP): Destination Canada provides comprehensive medical coverage with optional non-medical benefits, including AD&D, accidental dental, follow-up care, and companion support under an IRCC-compliant plan.
6. Group Medical Services (GMS): Best for competitive pricing
We rate GMS (Group Medical Services) 4/5 because it is one of the most cost-effective and straightforward options for Super Visa applicants.
As a well-established Canadian health insurer, GMS excels at providing strong, fundamental emergency medical coverage without forcing buyers to pay for the secondary benefits. Their plan easily meets all IRCC requirements (offering the mandatory $100,000 limit) and provides coverage for stable pre-existing conditions for applicants up to 80 years old.
While GMS requires upfront payment rather than monthly installments, their highly competitive baseline pricing and flexible deductible options (ranging from $0 to $1,000) make it very easy for budget-conscious sponsors to find an affordable policy.
Why choose GMS
- One of the most affordable options on the market
- Provides emergency prescription drug coverage with specified limits and duration
- Includes up to a 30-day supply of emergency prescriptions
- Covers pre-existing conditions that have been stable for 180 days
Unique selling point (USP): GMS delivers affordable, IRCC-compliant coverage with 30-day supply of prescription drugs, 180-day stable pre-existing support, and renewal flexibility.
7. 21st Century: Best for healthy travellers
PolicyAdvisor rating
We give 21st Century 4/5 for Super Visa insurance because it offers one of the most affordable, streamlined plans in Canada for healthy visitors, especially those under 60 with no major medical conditions.
21st Century offers distinct tiers of coverage. Their budget-friendly Basic Plan completely excludes pre-existing conditions, which results in drastically lower monthly premiums for healthy applicants. Like Secure Travel and Destination Canada, 21st Century also offers a highly popular monthly payment plan specifically for Super Visa holders, requiring just a two-month initial deposit and a small administration fee to meet IRCC guidelines.
Why choose 21st Century
- Ideal for healthy visitors under 60 with no major medical conditions
- Higher deductible options reduce monthly premiums
- Simple, essential coverage suitable for short or low-risk visits
- Monthly payment options for easier upfront cost management
Unique selling point (USP):21st Century delivers highly affordable baseline coverage for healthy visitors (with no age limit on their Basic Plan), backed by Manulife’s world-class claims network
How much does Super Visa insurance cost in Canada?
On average, Super Visa insurance costs between $1,100 and $4,500 per year for a standard $100,000 policy. The costs vary based on age, medical history, trip length, and coverage amount. Premiums rise with age and increase if pre-existing conditions are included. Choosing the right plan can help families manage costs while meeting IRCC requirements.
For example, premiums for a 75-year-old parent can vary significantly depending on the insurer, deductible, province of stay, trip length, and underwriting. Coverage for stable pre-existing conditions typically increases the cost. Always refer to live quotes with stated assumptions and insurer documentation for accurate pricing.
Super Visa insurance premiums differ based on age and whether you have pre-existing conditions. The table below provides illustrative annual costs for a plan with $100,000 in emergency medical coverage.
| Age | Without pre-existing conditions | With stable pre-existing conditions |
| 55 | $1,110.70 | $1,299.40 |
| 60 | $1,129.31 | $1,377.51 |
| 65 | $1,200.67 | $1,743.61 |
| 70 | $1,455.07 | $2,249.31 |
| 75 | $2,482.00 | $3,400.34 |
| 80 | $3,084.25 | $4,470.70 |
*Illustrative annual premiums for a Super Visa plan with $100,000 in emergency medical coverage. Costs vary by age and pre-existing conditions.
Need insurance answers now?
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.
How do pre-existing conditions affect Super Visa insurance?
Pre-existing medical conditions (such as high blood pressure, type 2 diabetes, or heart disease) directly impact your Super Visa insurance eligibility, premium costs, and overall coverage limits. Opting for a plan that covers pre-existing conditions typically increases the baseline premium by 30% to 80%.
To obtain coverage for these conditions, standard Canadian visitor insurance policies require the applicant to meet a strict stability clause. This clause mandates that the medical condition must remain completely unchanged for a specific “look-back period”, typically 90, 120, 180, or 365 days immediately preceding the policy’s effective date.
Which Super Visa insurance is best for parents with diabetes or hypertension?
The best Super Visa insurance for parents with diabetes or high blood pressure (hypertension) is a policy that includes comprehensive coverage for stable pre-existing conditions. Canadian providers like Secure Travel (RIMI), Destination Canada, GMS, and TuGo routinely insure visitors with these conditions. However, to be eligible for coverage, the applicant’s diabetes or hypertension must remain completely unchanged for a strict stability period, typically 90 to 180 days immediately prior to the policy’s start date.
Can I buy Super Visa insurance after arriving in Canada?
Whether you can buy Super Visa insurance after arriving depends entirely on your current visa status and application location.
1. Applying from outside Canada
If you are applying for your initial Super Visa from your home country, you cannot wait until you arrive to buy insurance. Immigration, Refugees and Citizenship Canada (IRCC) requires you to submit proof of a valid policy alongside your initial application. F
urthermore, Canadian Border Services Agency (CBSA) officers can ask to see your active policy upon landing. If you arrive without valid insurance, you risk being denied entry or restricted to a standard 6-month visitor stay.
2. Applying or renewing from inside Canada
You can legally purchase Super Visa insurance after arriving in Canada if you are currently in Canada on a standard visitor visa and applying to switch to a Super Visa or already on a Super Visa and need to renew an expiring one-year policy to maintain your legal status and extend your stay.
Note that if you purchase an insurance policy after your arrival date, Canadian insurers will apply a strict illness waiting period. While coverage for accidental injuries begins immediately, any sickness or disease will not be covered for a set timeframe, typically 48 hours to 7 days, depending on the provider and how long you have already been in Canada.
Can I buy Super Visa insurance from a foreign company in 2026?
Yes. As of a major policy update in 2025, Immigration, Refugees and Citizenship Canada (IRCC) officially allows Super Visa applicants to purchase mandatory emergency medical insurance from certain foreign insurance companies.
However, not every international travel insurance policy qualifies. To be accepted by IRCC, the foreign insurance policy must meet the standard Super Visa requirements (a minimum of $100,000 in coverage, valid for at least one year) and the foreign insurance company itself must pass strict Canadian regulatory criteria.
What happens if my Super Visa is denied after I buy insurance?
If your Super Visa is denied after you buy insurance, most providers in Canada will allow you to request a full refund, as long as you provide proof of visa refusal. To get your money back, you must submit the official IRCC rejection letter along with your policy details.
However, refund policies may vary by insurer, so it’s important to review the terms before purchasing. Many insurance providers in Canada, such as Manulife or 21st Century, offer hassle-free cancellation and full refunds in case of visa denial, ensuring you don’t lose your money.
What if my visa is approved, but travel plans change?
If your visa is approved but the applicant’s travel dates are delayed, you do not need to cancel the policy. Simply contact your broker to change the effective date of the policy before the original start date passes. If the parent or grandparent decides not to travel to Canada at all, you can still cancel the policy for a refund, though the administration fee may be slightly higher.
How to file a Super Visa insurance claim in Canada?
The Super Visa insurance claims process ensures that insured visitors can receive timely medical care in Canada without financial stress. It’s important to follow the correct steps to avoid claim denial or delays.
- Contact the insurer’s emergency assistance line immediately before or right after seeking medical care
- Follow the insurer’s instructions on approved hospitals or clinics to avoid out-of-network charges
- Collect and submit required documents, such as claim forms, medical records, itemized bills, and receipts
- Submit the claim within the insurer’s specified timeline (often 30–90 days)
- Track the claim status online or through customer service for updates until it’s processed and settled
How to get the most affordable Super Visa insurance quotes in Canada?
Finding affordable Super Visa insurance quotes in Canada doesn’t have to be overwhelming, especially when you have expert guidance. At PolicyAdvisor, we work directly with Canada’s best visitor travel insurance companies that offer this coverage. Whether you are looking for basic coverage or policies that include pre-existing condition protection and add-ons, we compare all the best options to help you save both time and money.
Our licensed insurance advisors can help you find the cheapest Super Visa insurance quotes based on your unique needs, medical history, and budget preferences.
We also offer lifetime after-sales support, whether you need help with renewals, claims, or updating your coverage. Schedule a call with us today to get customized plans based on your travel needs.
Frequently asked questions
What happens if my Super Visa is rejected after buying insurance?
If your Super Visa is denied, most insurance providers in Canada will offer a full refund, often minus a small administrative fee. To receive the refund, you must submit proof of visa rejection, usually the IRCC refusal letter, before the policy’s start date. It’s essential to review the refund policy at the time of purchase, as terms may vary. Trusted providers like Manulife, TuGo, and 21st Century typically allow hassle-free cancellations.
Are monthly payments available for Super Visa insurance?
While Super Visa insurance usually requires full upfront payment for one year, some providers now offer monthly payment options through approved Canadian brokers. These plans may involve a small financing fee or require a deposit up front. Monthly payments can make Super Visa insurance more affordable for families managing high premiums, especially for elderly applicants or those with pre-existing conditions.
Does Super Visa insurance cover prescription drugs and follow-up care?
Super Visa insurance typically covers emergency prescription medications related to a covered illness or accident, but it may not cover long-term medications or routine refills. Some plans include limited coverage for follow-up visits or diagnostic tests, especially if linked to the initial emergency. It’s important to review each plan’s benefit summary carefully or consult a licensed advisor to ensure you choose a policy that meets the specific health needs of your visiting parents or grandparents.
Will my Super Visa insurance cover travel to other provinces in Canada?
Yes, most Super Visa insurance policies provide coverage throughout all provinces and territories in Canada, as long as the insured person is temporarily residing in Canada. However, coverage levels may vary if you change your location permanently or travel outside Canada. Some plans also include limited emergency travel coverage for short trips to the U.S. or other countries. Always confirm with your insurer about any travel plans and review the territorial coverage limits in your policy to avoid surprises.
Explore the best Super Visa insurance providers in Canada for 2026. These plans protect parents and grandparents from emergency medical costs during long stays. We evaluated providers based on coverage limits, premiums, pre-existing condition support, flexibility, travel benefits, and customer service. This guide compares Allianz, TuGo, Manulife, Destination Canada, GMS, 21st Century, and Secure Travel (RIMI) to help families select a plan that balances cost, protection, and peace of mind.
Immigration, Refugees and Citizenship Canada. Report on Super Visa Income Requirement, Appeal Process, Special Circumstances – Temporary Resident Visas. Government of Canada.