 1-888-601-9980
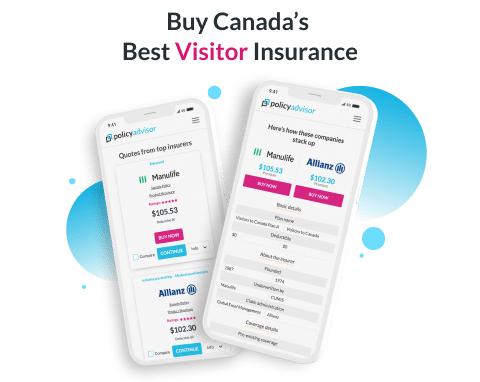
- The cheapest visitor insurance to Canada is offered by companies including Secure Travel, Travelance, Destination Canada, 21st Century, and more
- Visitor insurance costs depend on age, health, trip duration, and coverage needs, which helps in selecting a cost-effective plan
- Choose higher deductibles, family plans, and compare quotes across different insurers to get affordable visitor insurance policies
Secure Travel, Travelance, Destination Canada, and 21st Century are among the insurers offering some of the cheapest visitor insurance in Canada in 2026. Visitor insurance starts at $58.78/month for $100,000 in coverage for a 35-year-old visitor staying in Canada for 30 days, when choosing a $10,000 deductible. Premiums vary based on age, trip duration, coverage amount, health history, and deductible.
With more people arriving in Canada than before, the demand for the cheapest visitor insurance is surging. According to a report, Canada’s travel insurance market is projected to grow to $1.1 billion by 2030. The cheapest travel health insurance options in Canada for non-residents may vary based on the individual’s health and the coverage offered.
How much does Visitor Insurance cost?
Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.
Powered by

Top companies for the cheapest visitor health insurance
Several companies, such as Secure Travel, Manulife, Travelance, Destination Canada, and 21st Century, offer affordable visitor health insurance for non-residents in Canada. Here are some of the top providers for cheap travel insurance for visitors to Canada, offering affordable plans across different age groups, medical conditions, and coverage needs.
1. Secure Travel: Cheapest for comprehensive coverage
2. Travelance: Cheapest for monthly plans
3. Destination Canada: Cheapest for deductibles
4. 21st Century: Cheapest for longer stays
5. GMS: Cheapest for pre-existing conditions
6. Manulife: Cheapest for basic coverage
Cheapest travel insurance for visitors to Canada
In the section below, we personally reviewed visitor insurance quotes from multiple providers and compared them based on affordability across age groups, pre-existing medical conditions, monthly payment options, deductibles, and overall value.
1. Secure Travel: Cheapest for comprehensive coverage
Secure Travel ranks among the cheapest visitor insurance providers in Canada for comprehensive coverage. It typically costs between $94 and $240 for a 30-day policy with $100,000 in emergency medical coverage. Its affordable premiums, flexible deductible options, and monthly payment plans make it one of the most cost-effective choices for visitor and Super Visa insurance coverage.
Our methodology: To compare pricing consistently, we picked quotes using the same coverage details and trip length across insurers. The comparison uses a 30-day stay, $100,000 in emergency medical coverage, and no pre-existing conditions, with quotes collected for travellers at ages 35, 45, 55, 65, and 75. This shows how premiums change as the traveller’s age increases and how Secure Travel compares with other providers at each age.
Here is a comparison showing Secure Travel’s premiums for travellers aged 35 to 75:
| Age | Secure Travel | MSH | Destination Canada |
| 35 years | $94.20/month | $97.80/month | $94.80/month |
| 45 years | $101.70/month | $107.40/month | $119.40/month |
| 55 years | $110.10/month | $107.40/month | $119.40/month |
| 65 years | $133.20/month | $116.10/month | $171.00/month |
| 75 years | $240.00/month | NA | $291.90/month |
*Cost of $100,000 in coverage for a visitor travelling to Canada for a 30-day period
Key reasons why our advisors recommend Secure Travel:
- Emergency medical coverage available up to $1 million
- Includes up to $50,000 in accidental death and dismemberment (AD&D) coverage
- Automatic 72-hour policy extension for eligible travel delays at no additional cost
- Covers stable pre-existing medical conditions
- Enhanced plans include up to $3,000 for dental injuries and $500 for emergency dental pain relief
- Flexible deductible and payment options help reduce premium costs for visitors
2. Travelance: Cheapest for monthly plans
Travelance is the most cost-effective option for travellers who want to pay their premiums monthly rather than upfront. A 365-day Travelance visitor insurance policy with $100,000 in emergency medical coverage typically costs between $94 and $110 per month.
Its low upfront costs, automatic coverage extensions in eligible situations, such as when a travelling companion is hospitalized, and emergency medical benefits make it a strong option for visitors managing a tight budget.
Our methodology: To assess Travelance’s monthly pricing, we looked at the monthly premium required for a full 365-day visitor policy with $100,000 in emergency medical coverage. The comparison focuses on insurers that offer a monthly payment option for this coverage period. We compared the monthly cost at ages 35, 45, and 55 against MSH and Destination Canada.
Here is a table showing that Travelance is a more affordable monthly payment option:
| Age | Travelance | MSH | Destination Canada |
| 35 years | $94.60/month | $100.98/month | $106.12/month |
| 45 years | $102.50/month | $108.89/month | $131.06/month |
| 55 years | $110.72/month | $116.80/month | $131.06/month |
*Monthly cost of $100,000 in coverage for a visitor travelling to Canada for a 365-day period
Key reasons why our advisors recommend Travelance:
- Offers a family rate that includes coverage for dependent children at no additional cost
- Extended coverage for up to 558 days
- The premier plan includes coverage for accidental death and dismemberment for up to $100,000
- Pre-existing coverage under the premium option for those up to 79 years of age
- Flexible deductibles including $250, $500, $1,000, $5,000, and $10,000
3. Destination Canada: Cheapest visitor insurance for deductibles
Destination Canada is a good option for travellers looking to reduce premiums through higher deductible options. A 30-day policy with $100,000 in emergency medical coverage typically costs between $59 and $98, depending on the deductible selected. With deductible options available up to $10,000, it is a good choice for budget-conscious travellers comfortable with a higher deductible in exchange for lower premiums.
Our methodology: Instead of comparing premiums by traveller age, we compared how different deductible options affect the quoted premium. We used a 30-day policy with $100,000 in emergency medical coverage and compared Destination Canada’s monthly price at four deductible levels: $0, $500, $1,000, and $10,000. The results also show that the premium decreases as the deductible increases for Destination Canada, GMS, and Allianz, and the same holds for other insurers.
Here is a table depicting how Destination Canada is a more affordable option for deductibles:
| Deductible amount | Destination Canada | GMS | Allianz |
| $0 | $97.96/month | $135.47/month | $129.89/month |
| $500 | $83.27/month | $101.06/month | $110.41/month |
| $1,000 | $78.37/month | $103.54/month | NA |
| $10,000 | $58.78/month | NA/month | NA |
*Cost of $100,000 in coverage for a 35-year-old visitor travelling to Canada for a 30-day period, without pre-existing coverage
Key reasons why our advisors recommend Destination Canada:
- Multiple deductible options available, starting as low as $0 and going up to $10,000
- High coverage limits available up to $300,000
- Accidental death and dismemberment coverage of up to $150,000
- Monthly payment options are available for policies with coverage amounts above $50,000 and trip durations exceeding 6 months
- Nursing care benefit available up to $10,000, which is significantly higher than many other competitors
4. 21st Century: Cheapest visitor insurance to Canada for longer stays
21st Century is an affordable option for long-term stays. Its low-cost Basic Plan and flexible coverage durations make it especially attractive for healthy visitors, parents staying for several months, and travellers looking to reduce overall insurance costs on extended trips. The cost of a 21st Century visitor insurance policy typically ranges from $91 to $350, depending on the traveller’s trip duration.
Our methodology: In our comparison, we kept the traveller’s age fixed at 35 years. We compared the quoted cost of $100,000 in emergency medical coverage across three different stay lengths: 30, 90, and 120 days. This helped us focus on how trip duration alone affected the premium rates across the different insurers: 21st Century, Secure Travel, and TuGo.
Here is a table depicting how 21st Century is a more affordable option for longer stays:
| Duration of stay | 21st Century | Secure Travel | TuGo |
| 30 days | $90.52/month | $95.79/month | $105.40/month |
| 90 days | $262.80/month | $278.10/month | $306.00/month |
| 120 days | $350.40/month | $370.80/month | $408.00/month |
*Cost of $100,000 in coverage for a 35-year-old traveller visiting Canada without pre-existing coverage
Key reasons why our advisors recommend 21st Century:
- On the Monthly Payment Plan (MPP) option, the coverage limit resets to the full amount at the start of year two. The MPP offers a convenient payment option for those who want to reduce the upfront cost
- The Enhanced plan includes coverage for stable pre-existing medical conditions
- There is no age limit to get the Basic Plan, while Standard and Enhanced come with an age limit of up to 85 years
- High dental limits of up to $4000 under the Standard and Enhanced plans
5. GMS: Cheapest for pre-existing conditions
GMS is one of the strongest providers for travellers looking for affordable medical insurance for visitors in Canada with stable pre-existing medical conditions. GMS premiums for $100,000 in visitor insurance coverage with stable pre-existing condition coverage typically range from $106 to $455 per month for travellers aged 25 to 75. Moreover, its flexible plan options, lower medical screening requirements for younger visitors, and multiple deductible choices make it a good choice for those looking for visitor insurance to Canada.
Our methodology: The comparison uses $100,000 in visitor emergency medical coverage with stable pre-existing-condition coverage and takes into account different age groups: 25, 35, 45, 55, 65, and 75. We compared the quoted monthly premiums for GMS, 21st Century, and Manulife at each age to show how pricing changes across age groups when pre-existing conditions are covered.
Here is a table depicting how GMS is a more affordable option for pre-existing conditions:
| Age | GMS | 21st Century | Manulife |
| 25 years | $106.50/month | $113.10/month | $119.10/month |
| 35 years | $131.10/month | $120.00/month | $136.20/month |
| 45 years | $131.70/month | $146.70/month | $166.80/month |
| 55 years | $131.70/month | $155.40/month | $176.70/month |
| 65 years | $197.70/month | $254.40/month | $250.50/month |
| 75 years | $454.80/month | $469.50/month | $447.00/month |
*Cost of $100,000 in coverage for a visitor travelling to Canada for a 30-day period
Key reasons why our advisors recommend GMS:
- Multiple deductible options available, including $0, $100, $500, and $1,000
- Side-trip coverage outside Canada for eligible trips up to 30 days
- Automatic 48-hour extension during eligible travel delays
- Flexible coverage amounts: $25,000, $50,000, $100,000 or $150,000
- Accidental dental coverage of up to $2,000 per person for an accidental blow to the mouth
6. Manulife: Cheapest for basic coverage
Manulife offers multiple Basic, Standard, and Enhanced options, allowing visitors to choose a plan that matches both their budget and medical needs. Its basic coverage is one of the cheapest in the industry and comes with no maximum age limit. A 30-day Manulife visitor insurance policy with $100,000 in emergency medical coverage typically costs between $73 and $275 per month, depending primarily on the traveller’s age and coverage requirements.
Our methodology: We compared monthly premiums for $100,000 in emergency medical coverage over a 30-day stay at ages 25, 35, 45, 55, 65, and 75 years. Our comparison focused on basic coverage from Manulife, MSH, and Destination Canada, showing how quoted premiums vary across different age groups. The results help illustrate how the cost of visitor insurance changes as travellers get older and how Manulife’s pricing compares with other basic coverage options.
Here is a table depicting how Manulife is a more affordable option for basic coverage:
| Age (in years) | Manulife | MSH | Destination Canada |
| 25 | $73.20/month | $95.10/month | $77.10/month |
| 35 | $87.60/month | $97.80/month | $94.80/month |
| 45 | $106.50/month | $107.40/month | $119.40/month |
| 55 | $114.00/month | $107.40/month | $119.40/month |
| 65 | $148.50/month | $116.10/month | $171.00/month |
| 75 | $275.10/month | NA | $291.90/month |
*Cost of $100,000 in coverage for a visitor travelling to Canada for a 30-day period, without pre-existing coverage
Key reasons why our advisors recommend Manulife:
- Accidental death and dismemberment benefits of up to $25,000
- Emergency medical coverage of up to $200,000
- Pre-existing coverage under Standard and Enhanced (subject to a 180-day stability period)
- Emergency dental coverage of up to $4000 for treatment of natural teeth and repairs to dentures or other dental devices
- The Basic plan has no age limit, making it easily accessible to older travellers
Cheapest super visa insurance companies in Canada
The cheapest super visa insurance companies in Canada include Secure Travel, 21st Century, GMS, Destination Canada, TuGo, and Manulife. Secure Travel is the strongest overall pick when someone is looking for the cheapest visitor insurance in Canada for seniors or those who are above 60 years old. 21st Century offers the lowest base premiums for healthy seniors under 60, while GMS stands out for low-deductible plans.
TuGo offers the lowest premiums for super visa applicants with pre-existing conditions, while Manulife and Destination Canada offer lower rates for value-added and comprehensive benefits, respectively. To read more about how the premiums compare for super visa applicants in Canada, read our blog on the cheapest super visa in Canada.
Which is the cheapest visitor insurance for older applicants?
Travelance is one of the most affordable options for older visitors to Canada, particularly those aged 70 and above. It offers competitively priced plans that cater specifically to the needs of senior travellers, making it a top choice for emergency medical coverage in this age group. Travelance offers emergency medical coverage of up to $150,000 and specialized plans for seniors aged up to 79.
What factors affect the cost of visitor health insurance in Canada?
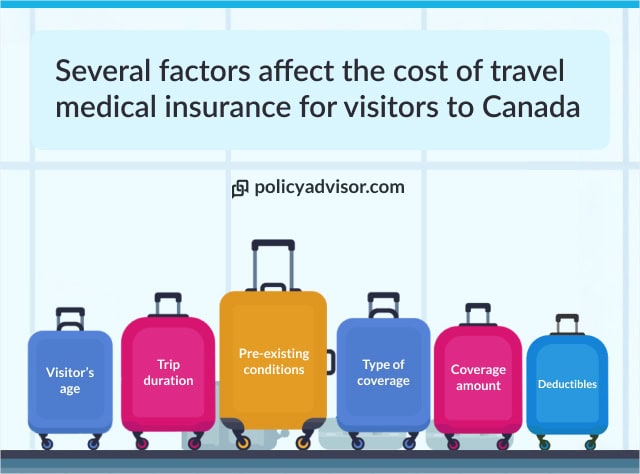
When determining the cost of your visitor insurance, factors such as age, health status, and the length of stay might come into play. Understanding these can help you anticipate and manage your insurance expenses effectively:
- Age: Insurance premiums often increase with age. For example, the cost for a 55-year-old individual is $129.60 per month, while it can be $328.80 per month for someone who is 75 years old
- Health status and pre-existing conditions: Plans with pre-existing coverage typically range from $92.70/month to $512.46/month, while without pre-existing coverage, they are around $69.00/month to $324.00/month (varies depending on traveller’s age, medical history, deductible selected, and coverage requirements)
- Trip duration: The longer you stay, the higher the overall premium, as the risk period for the insurer is extended
- Coverage limits and deductibles: Higher coverage limits generally result in higher premiums, while choosing a higher deductible can lower your insurance costs. However, this means you will pay more out-of-pocket in the event of a claim
- High-risk activities: If you plan to engage in activities deemed risky, such as skiing, mountain climbing, or other extreme sports, your insurance premium may increase due to the higher likelihood of injury. There are a few insurers, including TuGo, that provide coverage for these activities
Is visitor insurance mandatory for entering Canada in 2026?
No, travel health insurance for visitors to Canada is generally not mandatory for tourists entering Canada in 2026, but it is mandatory for a Super Visa. If you are applying for a Super Visa, you must provide proof of private health insurance for your visa approval. The policy must typically offer at least $100,000 in emergency medical coverage and remain valid for up to one year.
For tourists and short-term visitors, purchasing travel medical insurance is highly recommended. Medical care in Canada is expensive for non-residents, and even a simple hospital visit can cost thousands of dollars. By purchasing travel medical insurance, you protect yourself from financial risk and ensure you get access to proper medical care if an emergency arises during your stay. Read our detailed guide on whether you need visitor insurance for entering Canada.
How can I reduce the cost of my visitor insurance to Canada?
Here are some ways to reduce the cost of travel health insurance for visitors to Canada:
- Select your plan tier wisely: Visitor insurance plans typically come in Basic, Standard, and Enhanced options. Enhanced and Standard plans offer more benefits but also cost more. Compare the coverage carefully and choose a plan that matches your needs instead of paying extra for benefits you may not use
- Opt for family plans: Some insurers, such as Travelance, offer discounted family pricing that can help lower overall insurance costs. If you are travelling with family, opt for family rates
- Select adequate coverage limits: Choose a coverage amount based on your travel needs, so you do not pay for unnecessary protection
- Buy coverage only for your actual trip duration: Purchasing coverage for extra days unnecessarily increases premiums
- Compare the different insurers: Compare plan options offered by travel insurance companies in Canada and choose the one that fits your budget and coverage needs
Choosing the right deductible: Balancing cost and coverage
When selecting the cheapest travel insurance for visitors to Canada, choosing the right deductible is key to managing both premium costs and out-of-pocket expenses. A higher deductible lowers your premium but increases the amount you must pay before coverage kicks in.
Alternatively, a lower deductible results in higher premiums but reduces your financial burden if you need medical care. For short-term visitors in good health who are unlikely to require medical attention, a higher deductible can be a cost-effective option.
However, for older travellers or those with pre-existing conditions, a lower deductible may provide better financial protection by minimizing upfront costs in case of an emergency.
How can I get the cheapest visitor health insurance quotes in Canada?
You can find the most affordable visitor health insurance quotes for your trip to Canada by comparing plans online, and with PolicyAdvisor, the process takes less than a minute. Our licensed experts help you access and compare quotes from the best visitor health insurance companies in Canada, including trusted names like TuGo, Secure Travel, Travelance, and more.
We don’t just stop at finding you the cheapest premium. Our advisors guide you through the entire application process. We also provide dedicated after-sales support for claims or policy changes in the future. With PolicyAdvisor, getting the right coverage is fast, easy, and reliable.
Frequently asked questions
How can I ensure my insurance will cover emergency medical services in Canada?
To ensure your insurance covers emergency medical services in Canada, choose a more comprehensive plan with a higher coverage amount and added benefits such as emergency medical care, hospitalization, ambulance services, accidental dental coverage, paramedical service coverage, emergency evacuation coverage, and more.
Can I update my visitor insurance policy if my travel plans change?
Yes, you can usually update your visitor insurance policy if your travel plans change. Contact your insurance provider as soon as you know about the changes to adjust your coverage period or details. Be aware that changes may affect your premium or coverage terms, and there could be deadlines or additional fees.
Are there any discounts on visitor health insurance in Canada?
Yes, discounts on visitor health insurance in Canada are available, though they vary by insurer. Some companies offer discounts for purchasing extended coverage, paying premiums up front, or insuring multiple family members under one policy. Additionally, certain providers may have reduced rates for younger applicants or those in good health.
What are the common limitations and exclusions in visitor insurance policies?
Visitor insurance policies in Canada typically exclude pre-existing medical conditions unless specifically covered, as well as routine check-ups, preventive care, maternity expenses, and mental health treatments.
Other common exclusions include injuries from high-risk activities (such as extreme sports), alcohol- or drug-related incidents, and non-emergency treatments. Some policies also impose waiting periods for certain benefits, meaning coverage may not be immediate.
Can I get a refund if I cancel my visitor health insurance?
Yes, you can cancel your visitor health insurance plan for Canada and receive a refund, though the terms differ between insurers. Many providers offer full refunds if you cancel within the free-look period or before the policy takes effect. Once coverage has started, you may be eligible for a pro-rata refund for unused days, provided no claims have been made, minus any applicable fees.
Can I pay monthly for my visitor insurance policy?
Yes, you can pay monthly for your visitor insurance policy through several trusted Canadian providers. Travelance, Secure Travel, and Destination Canada Group offer affordable monthly payment options. These plans help visitors manage their finances better by spreading out premium payments instead of paying the full amount up front. Travelance is often one of the most affordable options for visitors seeking monthly payment plans.
Are there any hidden fees in cheap visitor insurance plans?
While cheap visitor insurance plans generally disclose all fees upfront, some plans might include hidden costs like higher deductibles, co-pays, or limited coverage that could lead to unexpected out-of-pocket expenses. Additionally, certain services or treatments may not be covered, resulting in additional costs.
What is the cheapest travel insurance for visitors to Canada?
The cheapest travel insurance for visitors to Canada starts at $58.78/month for $100,000 in coverage. The actual premium may, however, change based on the traveller’s age, trip duration, medical history, deductible, coverage amount, and pre-existing conditions. Higher deductibles can help lower premiums, while broader coverage or coverage for pre-existing conditions may increase the cost.
Which insurance company is the cheapest in Canada?
There is no single name for the cheapest insurance company in Canada. However, some of the insurers that offer the lowest rates include Secure Travel, Travelance, Destination Canada, 21st Century, GMS, and Manulife.
Looking for affordable visitor health insurance in Canada? This guide helps you find budget-friendly options without compromising coverage. Explore the best insurance companies providing the cheapest visitors to Canada insurance. Whether you’re visiting for a short trip or an extended stay, discover how to secure reliable insurance at the best price, ensuring peace of mind during your time in Canada.