 1-888-601-9980

- Whole life insurance policies accumulate a cash value. You can use this cash value to fund reduced paid-up insurance
- Reduced paid-up insurance means your guaranteed death benefit would only be your cash value, but you don’t have to pay any more premiums
- This option works for those who can no longer afford policy premiums, but still want to maintain some amount of guaranteed death benefit
Reduced paid-up insurance lets you exchange your whole life policy for a reduced guaranteed death benefit that doesn’t require monthly payments. This type of policy is ideal if you’ve built a steady amount of cash value in your whole life policy and no longer want or can’t afford to pay your monthly premiums.
While this may seem like an easy way to utilize a whole life policy’s cash value and get away with not having to foot your insurance bill later in life, it may mean the death benefit your family gets is significantly lower than you originally planned. PolicyAdvisor is in the business of providing policies, but we also want to help you reach your financial goals. If you use your cash surrender value to purchase a reduced paid-up policy, it’s vital to understand the terms and conditions of the transactions and what your alternatives are.
This article explains the details of reduced paid-up policies and goes over situations where it may be beneficial for your financial situation.
What is reduced paid-up insurance?
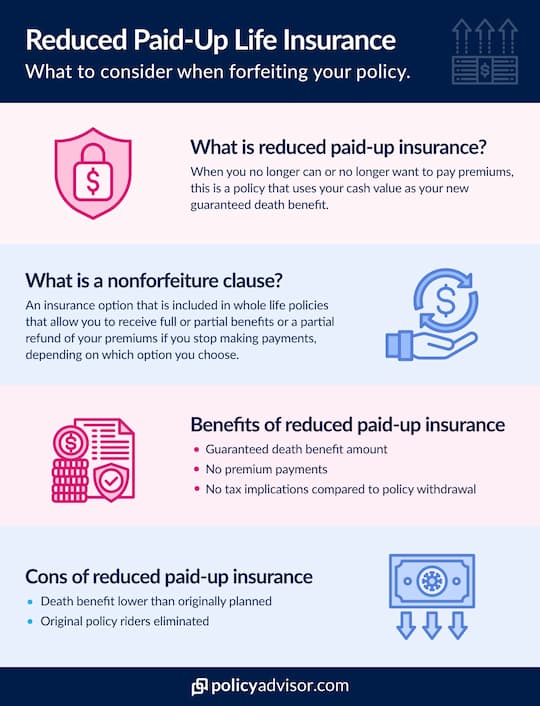
Reduced paid-up insurance is a non-forfeiture option available with many permanent life insurance policies, including some whole life and universal life policies. It lets you stop required premium payments while retaining a lower amount of life insurance coverage.
The insurer uses the policy’s accumulated cash value to calculate the reduced paid-up death benefit. The new death benefit is not necessarily equal to the cash value; it depends on the insurer’s calculation, the policy’s guarantees, the insured’s age, and the policy’s terms.
Once the reduced paid-up option is selected, no further premiums are required. The policy remains in force with the reduced death benefit, subject to its terms.
Need insurance answers now?
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.
What is a non-forfeiture clause?
A non-forfeiture clause is a provision in many permanent life insurance policies that provides options if you stop paying premiums. Rather than allowing the policy to lapse automatically, it may let you use the policy’s accumulated value to retain some benefit.
Common non-forfeiture options include:
- Cash surrender: Receive the policy’s cash surrender value in cash, subject to policy terms and potential tax consequences.
- Extended term insurance: Use the policy’s value to purchase term life insurance, generally with the same or similar death benefit for a limited period.
- Reduced paid-up insurance: Stop premiums while retaining a lower amount of paid-up permanent coverage.
- Premium loan or automatic premium loan: Use available policy value to cover premiums temporarily, where available.
Non-forfeiture clauses are available with universal life insurance, as well. However, with universal life policies, you choose a pre-selected investment portfolio based on your risk tolerance. As a result, the cash value of your universal life policy changes depending on the performance of the investment portfolio and can change the death benefit of a reduced paid-up policy or the term of an extended-term life policy.
Ultimately, non-forfeiture clauses are a great way to protect yourself in the event you’re unable to pay further premiums. It provides options on converting the cash value you’ve worked so hard to build.
How does reduced paid-up insurance work?
Reduced paid-up insurance works by using an eligible permanent life insurance policy’s available cash value to calculate a lower paid-up death benefit. Once selected, no further premiums are required, while the policy remains in force at the reduced coverage amount, subject to its terms.
If you can no longer afford premiums or no longer want to continue paying them, you may be able to use the reduced paid-up non-forfeiture option on an eligible permanent life insurance policy.
The insurer uses the policy’s available cash value to calculate a new, reduced paid-up death benefit. Once this option is selected, no further premiums are required, and the policy remains in force with the lower death benefit, subject to its terms.
Reduced paid-up insurance is generally available with some permanent life insurance policies, including certain whole life and universal life policies. Availability, eligibility rules, minimum policy duration, and the calculation method vary by insurer and product.
Term life insurance does not build cash value and therefore does not offer a reduced paid-up non-forfeiture option. A term policy’s death benefit is generally payable if the insured dies while the policy is in force during the selected term.
Our advisors’ take on the reduced paid-up policy process
Suppose you purchased a whole life policy seven years ago with a death benefit of $200,000. It has built up significant cash value over this time of around $50,000.
You’re planning to retire in the next year. Your income will significantly drop, so you’ll have to reduce your monthly expenses as well. You speak with a life insurance advisor to see how you can reduce your monthly premiums.
In this discussion, your advisor might suggest using your whole life policy’s cash value to purchase a reduced paid-up policy. This reduces your guaranteed death benefit to $50,000 but also eliminates premium payments.
Such a solution is ideal for retirement because children are often grown up (meaning you no longer have financial dependents). Further, retirees commonly have little or no debts. If having a significant death benefit paid to your beneficiaries isn’t as important to you or you have estate funds saved up separately and you’d rather have the extra premium payments in your pocket, this might be a good option for you.
What’s the difference between reduced paid-up insurance and paid-up additions?
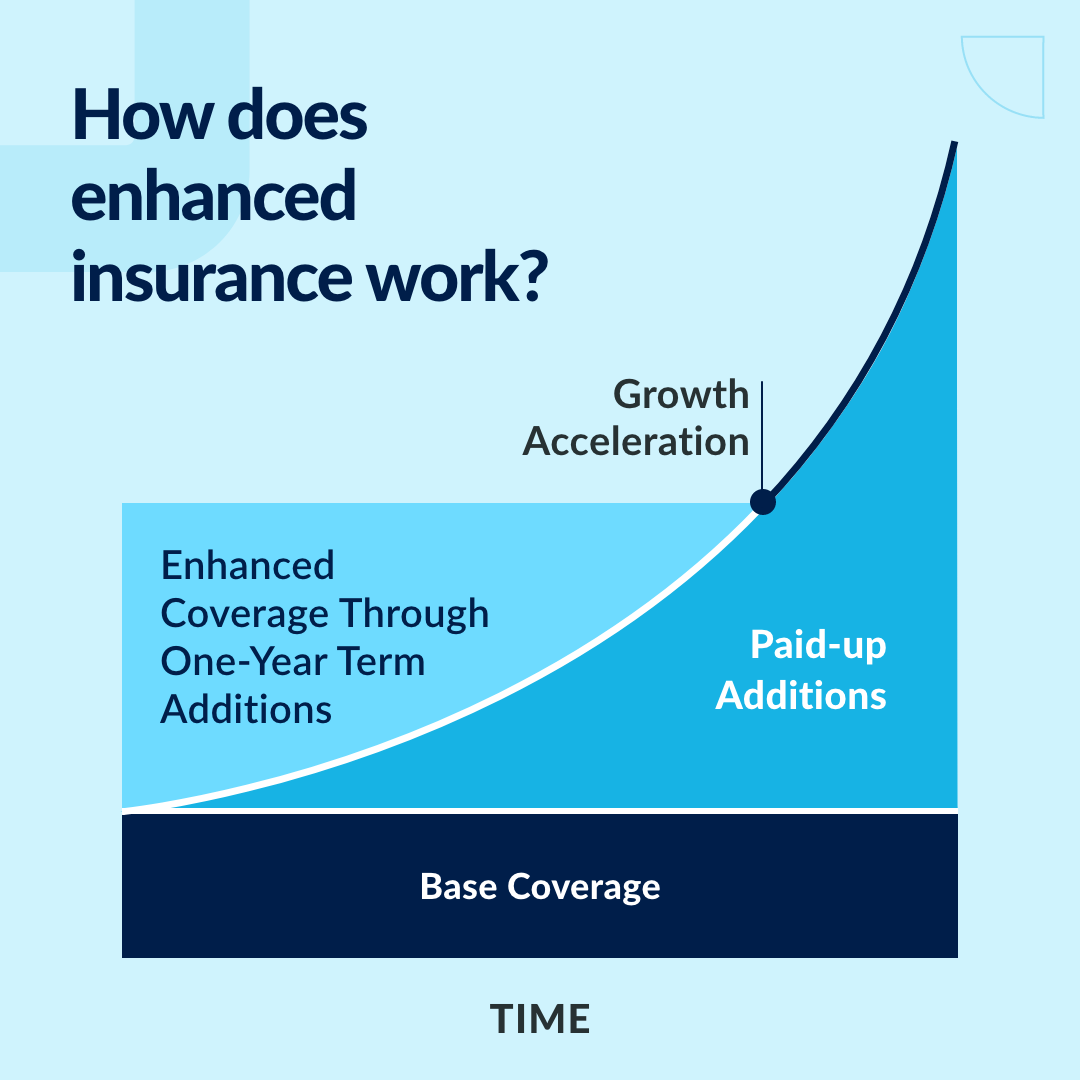
Reduced paid-up insurance and paid-up additions both involve paid-up life insurance, but they serve opposite purposes. Reduced paid-up insurance lets you stop required premiums while keeping a lower paid-up death benefit. Paid-up additions use declared dividends to add coverage to a participating whole life policy that generally remains in force, potentially increasing its death benefit and cash value.
Reduced paid-up insurance
Reduced paid-up insurance is a non-forfeiture option. If you stop paying premiums on an eligible permanent life insurance policy, the insurer may use the policy’s available cash value to calculate a new, lower paid-up death benefit. Once selected, no further premiums are generally required. The policy remains in force at the reduced coverage amount, subject to its terms.
The new death benefit is not necessarily equal to the policy’s cash value. It depends on the insurer, policy, insured’s age, policy duration, available cash value, outstanding loans, and any applicable non-guaranteed values.
Paid-up additions
Paid-up additions let you swap your whole life policy’s dividends for additional life insurance coverage. Unlike reduced paid-up insurance, you still pay the monthly premium to your original whole life policy, as your whole life policy is still in force, just with an increased death benefit amount.
Paid-up additions are usually bought as a policy rider to your initial whole life insurance purchase. A rider is an optional add-on that supplements your whole life policy. In contrast, reduced paid-up insurance is a non-forfeiture clause option. Ultimately, paid-up additions are for someone who wants a larger death benefit without paying additional premiums.
| Feature | Reduced paid-up insurance | Paid-up additions |
| What it does | Changes an existing eligible policy’s status after premiums stop | Adds coverage to a policy that generally remains in force |
| Premiums on the base policy | Stop | Generally continue |
| Source of funding | Policy’s available cash value | Declared policy dividends, where available |
| Effect on death benefit | Usually lowers it | May increase it |
| Effect on cash value | The original policy no longer continues accumulating cash value in the same way | May increase the policy’s cash value |
| Best for | Someone who cannot or does not want to continue paying premiums but wants some coverage | Someone receiving dividends who wants to increase coverage |

What’s the difference between reduced paid-up insurance and extended-term insurance?
Reduced paid-up insurance and extended-term insurance are both non-forfeiture options for eligible permanent life insurance policies. The main difference is that reduced paid-up insurance retains a lower amount of permanent coverage for life, while extended-term insurance uses the policy’s available value to provide term coverage for a limited period.
Reduced paid-up insurance
With reduced paid-up insurance, the insurer uses the policy’s available cash value to calculate a new, lower paid-up death benefit. Once selected, no further premiums are generally required, and the policy remains in force with the reduced coverage amount, subject to its terms.
The new death benefit is not necessarily equal to the policy’s cash value. It depends on the insurer, policy, insured’s age, policy duration, available cash value, outstanding loans, and any applicable non-guaranteed values.
Extended-term insurance
Extended-term policies provide a term life insurance policy that no longer requires premium payments. The cash value that has been accumulated from a whole life insurance policy is used to purchase term life insurance with a death benefit as close to your original whole life death benefit as possible. Because it’s a term life policy, the death benefit is only payable if you pass away during a particular period.
For example, say you had a whole life policy with a death benefit of $100,000 and an accumulated cash value of $10,000. With extended-term policies, the insurance provider would calculate how many years it would take for premium payments of $10,000 (your cash value) to equal $100,000 (your death benefit) in coverage. Say this takes 20 years. Therefore, you would exercise the non-forfeiture clause to purchase a term 20 policy with a death benefit of $100,000 and pay no premiums at all, it’s already paid for by your cash value.
| Feature | Reduced paid-up insurance | Extended-term insurance |
| Type of coverage after the change | Permanent paid-up life insurance | Term life insurance for a limited period |
| Premiums after the change | None | None |
| Death benefit | Lower permanent death benefit | Often closer to the original death benefit |
| Coverage duration | Generally for life, subject to policy terms | Limited period determined by the insurer’s calculation |
| Best for | Lifelong coverage at a reduced amount | Higher temporary coverage for a defined period |
What’s the difference between reduced paid-up insurance and a cash surrender?
Reduced paid-up insurance and a cash surrender both use a permanent life insurance policy’s available cash value, but they produce very different outcomes. Reduced paid-up insurance lets you stop premiums while retaining a lower paid-up death benefit; a cash surrender ends the policy and provides its available surrender value in cash.
Reduced paid-up insurance
Choose reduced paid-up insurance if you can no longer afford or no longer want to pay premiums but still want a guaranteed death benefit for your beneficiaries. The coverage amount will be lower than the original policy, and the policy will no longer continue accumulating cash value in the same way.
Cash surrender
Choose a cash surrender if you no longer need life insurance coverage and want to receive the policy’s available surrender value in cash. Before surrendering, ask the insurer for the cash surrender value, outstanding loan balance, adjusted cost basis, and an estimate of any potential taxable policy gain.
| Feature | Reduced paid-up insurance | Cash surrender |
| Premiums after the change | None | None |
| Death benefit | A lower paid-up death benefit remains; it is calculated using the available cash value and is not necessarily equal to it | No life insurance coverage remains |
| Cash received | No | Yes, the policy’s cash surrender value, subject to policy terms |
| Coverage continues | Yes, at a reduced amount | No |
| Potential tax outcome | Generally, selecting the option is not itself a taxable disposition, but policy-specific rules apply | A surrender may create taxable income if the amount received exceeds the policy’s adjusted cost basis |
| Best for | Someone who still wants some life insurance coverage | Someone who no longer needs coverage and wants to receive the policy’s available surrender value |
Pros and cons of reduced paid-up insurance
| Pros | Cons |
| Lets you stop required premium payments | The death benefit is usually much lower than the original coverage amount |
| Retains some life insurance coverage rather than surrendering the policy | Reduces or ends further cash-value accumulation under the original policy structure |
| May preserve a guaranteed death benefit | May not provide enough coverage for current or future dependants |
| Can help someone manage expenses during retirement or an income reduction | Once selected, the decision may be difficult or impossible to reverse |
| May be available without a new medical underwriting process | Availability and calculation methods vary by insurer and policy |
| Death benefit paid to a named individual beneficiary is generally tax-free | Later loans, withdrawals, or surrender can have tax consequences |
Who should consider reduced paid-up insurance?
Reduced paid-up insurance may suit someone who:
- Can no longer afford premiums but wants to retain some life insurance coverage.
- No longer needs the full original death benefit because debts have been repaid or dependants no longer rely on their income.
- Wants permanent coverage rather than temporary extended-term coverage.
- Wants to avoid surrendering the policy and losing all life insurance protection.
- Has sufficient cash value for the insurer to calculate a meaningful reduced paid-up death benefit.
It may not be suitable if:
- You still need the original death benefit for income replacement, mortgage protection, estate liquidity, or business planning.
- Your cash value is too low to produce a useful reduced paid-up death benefit.
- You want access to the policy’s cash value now.
- You can afford to continue premiums and want to preserve the policy’s original coverage and cash-value growth.
Tax treatment of reduced paid-up insurance in Canada
In Canada, choosing reduced paid-up insurance is generally a non-forfeiture option rather than a surrender of the policy. As a result, selecting this option does not automatically create taxable income.
However, tax treatment can depend on the policy’s adjusted cost basis, prior loans or withdrawals, policy ownership, and whether the policy remains exempt under the Income Tax Act. A later surrender, withdrawal, or policy loan may have tax consequences; any amount above the policy’s adjusted cost basis may be taxable income.
A death benefit paid to a named individual beneficiary is generally received tax-free. Corporate-owned policies involve additional tax considerations, including the adjusted cost basis and capital dividend account.
Because tax rules and policy terms can be complex, obtain confirmation from the insurer and consult a qualified tax professional before making a decision.
Should you purchase reduced paid-up insurance?
Reduced paid-up insurance is a good option if you don’t want to continue premium payments but still want a death benefit for your beneficiaries. Just remember that the death benefit is usually reduced when compared to your whole life policy’s original payout amount.
This type of insurance is ideal if you no longer need the total amount of your whole life policy’s death benefit because you have fewer debts and/or financial dependents now. You might also consider it if you can no longer afford your whole life insurance premiums.
Whether you should purchase a reduced paid-up policy depends on your life circumstances, similar to any life insurance policy. Speak to one of PolicyAdvisor’s licensed insurance advisors today to determine whether a reduced paid-up insurance policy is right for you.
Frequently asked questions
What is reduced paid-up insurance?
Reduced paid-up insurance is a non-forfeiture option that lets you stop paying premiums on an eligible permanent life insurance policy while keeping a lower amount of paid-up coverage. The insurer uses the policy’s cash value to calculate the new death benefit.
Is the new death benefit equal to my cash value?
No. The insurer uses the cash value to calculate a reduced paid-up death benefit, but the new death benefit is not necessarily equal to the cash value. The calculation depends on the policy, insurer, insured’s age, and policy terms.
Does reduced paid-up insurance last for life?
Reduced paid-up insurance is generally permanent coverage, so it remains in force for life once selected, subject to the policy terms. Unlike extended-term insurance, it is not designed to expire after a fixed period.
Can I choose reduced paid-up insurance on a term policy?
Generally, no. Term life insurance usually does not build cash value and therefore does not offer a reduced paid-up non-forfeiture option. Reduced paid-up insurance is generally associated with permanent life insurance policies.
Is reduced paid-up insurance taxable?
Choosing reduced paid-up insurance does not automatically create taxable income in Canada. However, later withdrawals, policy loans, or a surrender may have tax consequences, particularly if the amount accessed exceeds the policy’s adjusted cost basis.
Can I reverse reduced paid-up insurance?
Usually, no. Once reduced paid-up insurance is selected, it may be difficult or impossible to restore the original policy. Ask the insurer about reinstatement rules, deadlines, and whether a new application or underwriting is required.
The information above is intended for informational purposes only and is based on PolicyAdvisor’s own views, which are subject to change without notice. This content is not intended and should not be construed to constitute financial or legal advice. PolicyAdvisor accepts no responsibility for the outcome of people choosing to act on the information contained on this website. PolicyAdvisor makes every effort to include updated, accurate information. The above content may not include all terms, conditions, limitations, exclusions, termination, and other provisions of the policies described, some of which may be material to the policy selection. Please refer to the actual policy documents for complete details. In case of any discrepancy, the language in the actual policy documents will prevail. All rights reserved.
If something in this article needs to be corrected, updated, or removed, let us know. Email editorial@policyadvisor.com.
If you have a whole life insurance policy and no longer want to pay premiums, you may use your cash value to fund reduced paid-up insurance. This means that you can choose to stop paying premiums and your guaranteed death benefit would be the cash value, rather than the original agreed-upon coverage amount. Reduced paid-up insurance is different from paid-up additions, which is additional insurance that can be purchased using policy dividends.